Adding or Removing a Partner in an LLP in 2026: Form 4 and Form 3 Within 30 Days, Designated Partners, GST Update and Tax on Retirement
Adding or removing a partner in an LLP needs Form 4 and, where the agreement changes, Form 3 at the MCA within 30 days, or fees run daily.
Three friends run a ceramic trading LLP in Morbi. One partner is moving to Canada and wants to retire, and a cousin is joining with fresh capital. They signed a one-page letter and changed the bank signatories, but nothing has been filed with the MCA, the LLP agreement still shows the old profit ratio, and the retiring partner wants his capital paid out in cash.
LLPs are popular in Saurashtra because they combine a firm's flexibility with limited liability, but every change in partners has filings and tax points of its own. Here is how admission and retirement work in 2026.
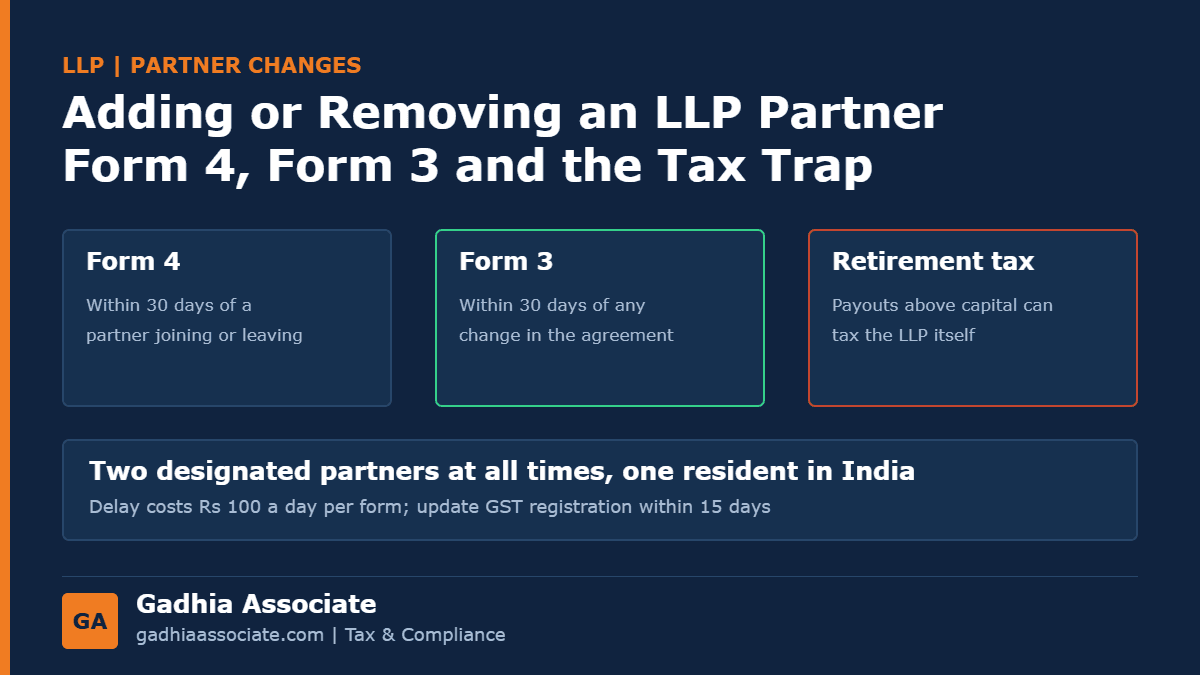
In short: An LLP must always have at least two partners and two designated partners who are individuals, at least one of them resident in India. A new partner needs a supplementary LLP agreement, and a new designated partner also needs a DIN and gives consent in Form 9. The LLP files Form 4 within 30 days of any partner joining or leaving, and Form 3 within 30 days of any change to the LLP agreement, such as capital or profit ratios; delays cost Rs 100 a day for each form. GST registration must be amended for the change in partners. Paying a retiring partner more than the balance in his capital account can create capital gains tax for the LLP itself.
Our team handles LLP agreements, Form 3 and Form 4, GST amendments and the tax side of partner changes. The details are at the end of this guide.
Minimum partners and designated partners
- Partners: at least two at all times.
- Designated partners: at least two, who must be individuals, with at least one resident in India.
- DIN: every designated partner needs a DIN and must keep the yearly KYC up to date. See DIR-3 KYC.
- Order matters: admit the new partner before the retiring one leaves, so the LLP never falls below the minimum.
Admitting a new partner
- Agree the terms: capital contribution, profit share, duties and whether the person will be a designated partner.
- Supplementary LLP agreement: signed by all partners and stamped under Gujarat stamp law.
- Consent: a new designated partner gives consent in Form 9 and needs a DIN and digital signature.
- Form 4: within 30 days of admission.
- Form 3: within 30 days of the change in the LLP agreement.
Retirement of a partner
- Notice: as provided in the LLP agreement, usually written notice to the other partners.
- Settlement: the retiring partner's capital and share of profits are worked out to the date of retirement.
- Filings: Form 4 for the cessation and Form 3 for the revised agreement, each within 30 days.
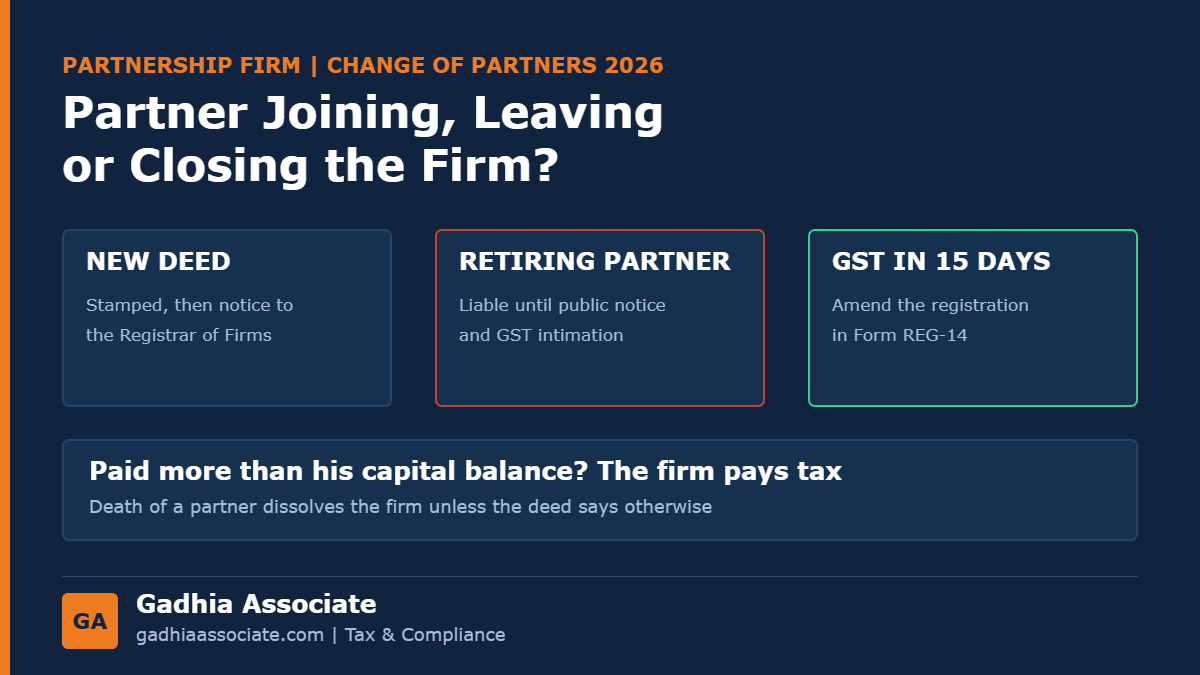
- Liability: the retiring partner can remain liable to outsiders who deal with the LLP without knowing of the retirement, until the change is filed, so file quickly.
Tax when a partner leaves
- Payments above capital: since 2021, money or assets paid to a partner on retirement, over and above the balance in his capital account, can be taxed as capital gains in the hands of the LLP.
- Assets given to a partner: stock or a capital asset handed over on reconstitution is treated as transferred at fair market value.
- Plan the payout: revaluation, goodwill and the timing of payments change the tax result, so work it out before the settlement is signed.
- Partners' remuneration: salary and interest to partners must follow the limits written into the agreement. See what the deed must say.
Other updates
- GST: adding or removing partners is a core change in GST registration, applied for with REG-14 within 15 days and approved by the officer.
- Bank: update the mandate and signatories after the filings.
- Licences: IEC, FSSAI, Udyam and other registrations naming partners.
- Annual filings: the changes flow into Form 8 and Form 11. See LLP annual compliance.
Back to the Morbi LLP. The cousin is admitted first through a supplementary agreement, with a DIN and Form 9 as a designated partner, and Form 4 and Form 3 are filed. The retiring partner's settlement is worked out to his capital balance plus his share of profits to the retirement date, with any excess payment checked for the LLP's capital gains tax before it is paid. Then his cessation goes in Form 4, the GST registration and bank mandate are updated, and the LLP stays at three partners and two designated partners throughout. For a firm rather than an LLP, see our guide to adding or removing a partner in a partnership firm.
How we help
- Supplementary LLP agreements for admission and retirement
- DIN, digital signatures and Form 9 for designated partners
- Form 3 and Form 4 within 30 days
- Tax working on retirement payouts and asset transfers
- GST amendment, bank mandate and licence updates
- Annual LLP filings and, where needed, closure or conversion
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. LLPs and firms from Junagadh, Rajkot, Morbi, Jamnagar and Gondal come to our Junagadh office, where same-day appointments are available. LLP work for clients elsewhere in India is handled online.
Partner joining or leaving your LLP? Get the agreement, filings and tax right in one go. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
Which form is filed for a change in LLP partners?
Form 4, within 30 days of a partner joining or leaving, along with Form 3 if the LLP agreement changes.
What is the penalty for late filing of Form 3 or Form 4?
An additional fee of Rs 100 for each day of delay, for each form.
How many designated partners does an LLP need?
At least two, who must be individuals, with at least one resident in India.
Does a new designated partner need a DIN?
Yes, along with a digital signature and consent in Form 9.
Is tax payable when a partner retires from an LLP?
It can be. Money or assets paid above the partner's capital balance can be taxed as capital gains in the hands of the LLP.
Do I need to update GST after a partner change?
Yes. Adding or removing partners is a core amendment, applied for within 15 days.
Position as of 23 October 2026, under the LLP Act, 2008 and rules, and the tax provisions on reconstitution as carried into the Income-tax Act, 2025. Your LLP agreement can add conditions, so take advice on your own facts.