Adding or Removing a Partner from a Partnership Firm in 2026: Retirement, Death, Dissolution, New Deed, GST and Income Tax in Gujarat
Adding or removing a partner from a partnership firm needs a new deed, notice to the Registrar, a GST amendment within 15 days and a tax check.
Three friends have run a tiles and sanitaryware showroom in Junagadh for eleven years. One of them decides to move to Surat. They agree that he will take his capital of Rs 20 lakh and another Rs 15 lakh for his share of the goodwill, sign a one-page retirement letter on stamp paper, and carry on. Nobody tells the Registrar, the GST office or the bank.
Three years later, a GST demand against the firm lands on the partner who left. The firm, meanwhile, learns that the extra Rs 15 lakh it paid him was taxable in its own hands. A change of partners is easy to agree and easy to get wrong. Here is what has to be done when a partner joins, leaves or dies, or when the firm closes.
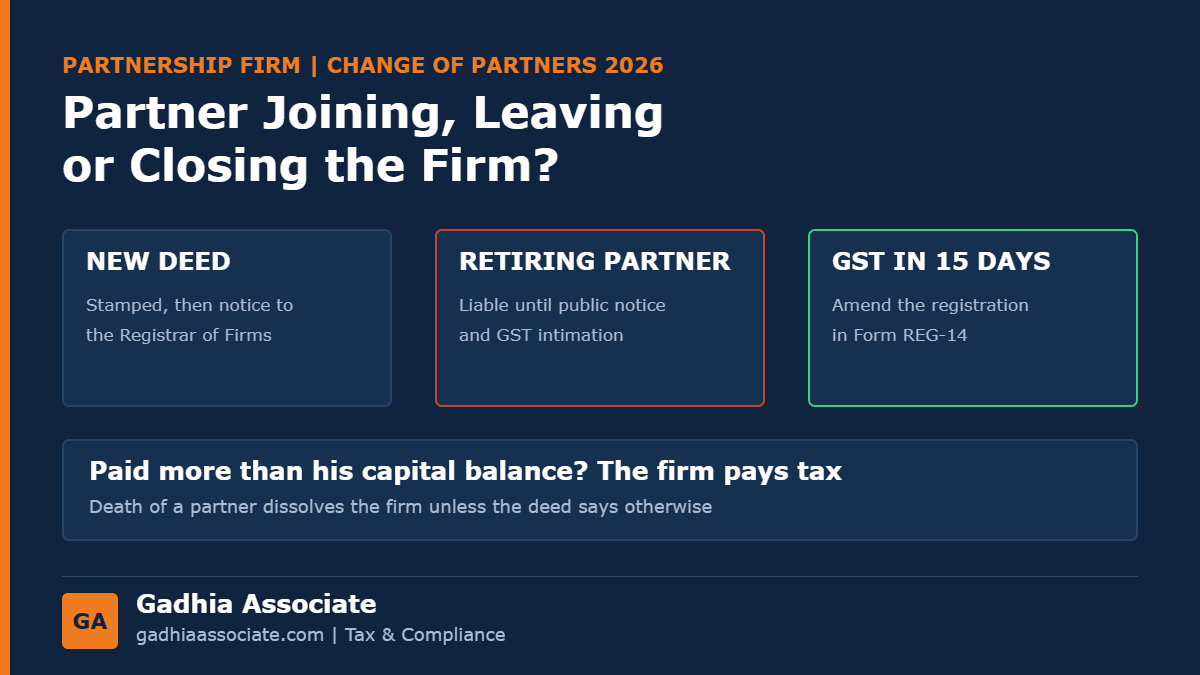
In short: A change of partners is recorded in a fresh or supplementary partnership deed, stamped under the Gujarat Stamp Act. For a registered firm, notice goes to the Registrar of Firms, and a retirement or dissolution also needs a public notice, without which the outgoing partner stays liable to outsiders. The GST registration is amended in Form REG-14 within 15 days, and a retiring partner must inform the GST department within one month or remain liable for the firm's later dues. For income tax the firm keeps its PAN, but when a partner receives more than the balance in his capital account, or takes stock or an asset, the firm pays tax on the difference under Sections 8 and 67(10) of the Income-tax Act, 2025. Unless the deed says otherwise, the death of a partner dissolves the firm.
When a new partner joins
- Consent: all existing partners must agree, unless the deed says otherwise.
- Deed: a supplementary or fresh deed stating the new capital, profit shares, working partners, remuneration and interest. Remuneration to the new partner is deductible only from the date of the deed, as our guide to what the partnership deed must say explains.
- Liability: the new partner is not liable for the firm's acts before he joined.
- Capital brought in as property: if he brings land or another asset instead of cash, the value recorded in the firm's books is treated as his sale price for capital gains, and stamp duty applies on the property.
- TDS: the firm deducts tax on remuneration and interest to every partner above Rs 20,000 a year. See TDS on payments to partners.
When a partner retires
- How: with the consent of all partners, as the deed provides, or in a partnership at will, by written notice to the others.
- Retirement deed: settle in writing his capital, current account, share of profit up to the date, and any amount for goodwill.
- Public notice: until public notice of the retirement is given, the retired partner and the firm remain liable to outsiders for each other's acts. For a registered firm, that means notice to the Registrar and publication in the Official Gazette and a local-language newspaper.
- GST intimation: the retiring partner or the firm must inform the GST department of the retirement within one month. Otherwise his liability for the firm's GST dues continues until the day the intimation is received. In 2025, a High Court upheld recovery from a partner who gave it almost four years after he had retired.
- Bank and guarantees: get his name removed from the account mandate, and a written release from any personal guarantee he gave for the firm's loans.
- Unsettled accounts: if the firm keeps using his money without settling, he can claim a share of the later profits, or interest at 6% a year.
The tax on what a retiring partner takes
Two rules, in force since 2021 and now in Sections 8 and 67(10) of the Income-tax Act, 2025, the old Sections 9B and 45(4), decide the tax when a firm is reconstituted:
- Money or assets worth more than his capital balance: the excess is taxed as capital gains in the firm's hands. Revaluation of assets and self-generated goodwill credited to his account are ignored in working out the balance.
- Stock or a capital asset given to him: the firm is treated as having sold it to him at market value, and pays tax on the profit.
An example: the Junagadh partner's capital account stood at Rs 20 lakh and the firm paid him Rs 35 lakh. The extra Rs 15 lakh is a capital gain of the firm, not a tax-free settlement. Had he taken tiles worth Rs 15 lakh instead, the firm would be taxed as if it had sold them at market price, and GST would apply on them too.
Two more points. The firm keeps its PAN, and the change is reported in its return. But the retired partner's share of any business loss brought forward cannot be carried forward by the firm.
When a partner dies
- The default rule: unless the deed says otherwise, the death of a partner dissolves the firm. A clause that the firm will continue with the surviving partners, with or without the heirs, avoids this.
- Two-partner firms: a firm of two partners ends on the death of one, whatever the deed says, because a firm needs at least two partners. The survivor must form a new firm or carry on as a proprietor, with a new PAN and GST registration.
- The estate: it is not liable for the firm's acts after the death, and no public notice is needed for this.
- The heirs: they are entitled to his capital and share, with the same right to later profits or 6% interest until the accounts are settled.
- If the firm continues: the same steps follow, namely a new deed, the Registrar, the GST amendment and the bank.
Stamp duty and the Registrar in Gujarat
- New or supplementary deed: where the capital is increased, 1% of the additional capital, up to Rs 10,000. Where the capital is unchanged, a small fixed duty.
- Retirement or dissolution deed: a small fixed duty, unless immovable property passes to a partner who did not bring it in. Then conveyance duty of 4.9% of the market value applies on that property.
- Registrar of Firms: for a registered firm, notice of the change or dissolution in the prescribed form, with the deed. If the firm was never registered, this is the time to do it, as our guide to partnership firm registration in Gujarat explains.
The checklist after any change of partners
- Deed signed, stamped and notarised.
- Registrar of Firms: notice of the change, and public notice for a retirement or dissolution.
- GST: amendment in Form REG-14 within 15 days. A change of partners needs the officer's approval.
- Bank: new mandate and KYC, and the lender's consent where there are loans.
- Income tax: update the partners' details on the portal and in the return.
- Other registrations: Udyam, IEC, FSSAI, professional tax, shop intimation, PF and ESIC.
Closing the firm altogether
- How: by agreement of all partners, by notice in a partnership at will, or by order of the court, recorded in a deed of dissolution.
- Settling accounts: outside creditors are paid first, then partners' loans, then capital, and the balance is shared in the profit-sharing ratio.
- Tax on what partners take: assets and stock taken over by partners are taxed in the firm's hands at market value, and GST is payable on stock and capital goods on which credit was taken.
- GST: apply for cancellation within 30 days and file the final return. Our guide to GST registration cancellation has the steps.
- Income tax and the rest: file the last return, surrender PAN and TAN, and close the bank accounts and other registrations.
- Public notice: until it is given, the partners remain liable for each other's acts.
If the worry is unlimited liability and not the business itself, converting may be better than closing. See our guide to converting a partnership firm into an LLP.
What we do for you
- Draft the admission, retirement, reconstitution or dissolution deed, and work out the stamp duty
- Work out the outgoing partner's dues, and the tax on them, before the deed is signed
- File the notice with the Registrar of Firms and arrange the public notice
- Amend the GST registration and file the retiring partner's intimation
- Update the bank, income tax records and other registrations
- On dissolution, cancel GST, file the final returns and close the registrations
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients across Saurashtra and Gujarat, with a 5.0 Google rating from more than 100 reviews. Partnership firms from Junagadh, Keshod, Rajkot, Jetpur, Veraval, Porbandar and Amreli come to our Junagadh office, where same-day appointments are available. Fixed-fee plans are available.
Is a partner joining or leaving your firm? Get the paperwork right first. Call +91 82005 28355 or message us on WhatsApp. The first consultation is free.
Frequently asked questions
How do you add a new partner to a partnership firm?
With the consent of all partners, a supplementary or fresh deed, notice to the Registrar of Firms and a GST amendment within 15 days.
Is a retired partner liable for the firm's debts?
For debts before his retirement, yes, unless the creditor agrees to release him. For later acts, he remains liable to outsiders until public notice is given, and for GST dues until the department is informed.
Does a partnership firm dissolve on the death of a partner?
Yes, unless the deed provides that it will continue. A firm with only two partners always ends.
Is the amount paid to a retiring partner taxable?
The part above the balance in his capital account is taxed as capital gains in the firm's hands under Section 67(10) of the Income-tax Act, 2025.
Does the firm need a new PAN or GST number when partners change?
No, if the firm continues. The PAN stays and the GST registration is amended. A new PAN and registration are needed only if the firm is dissolved.
What is the stamp duty on a retirement or dissolution deed in Gujarat?
A small fixed duty in ordinary cases, and conveyance duty of 4.9% on any immovable property that passes to a partner who did not bring it in.
Position as of 6 October 2026. Stamp duty and the Registrar's procedure change by notification, and the tax on a reconstitution depends on the firm's accounts and deed. Take advice on your own firm before you sign.