GST on Diwali Offers in 2026: Buy-One-Get-One, Free Gifts and ITC Reversal, Discounts After Sale, Gift Vouchers and Exchange Offers
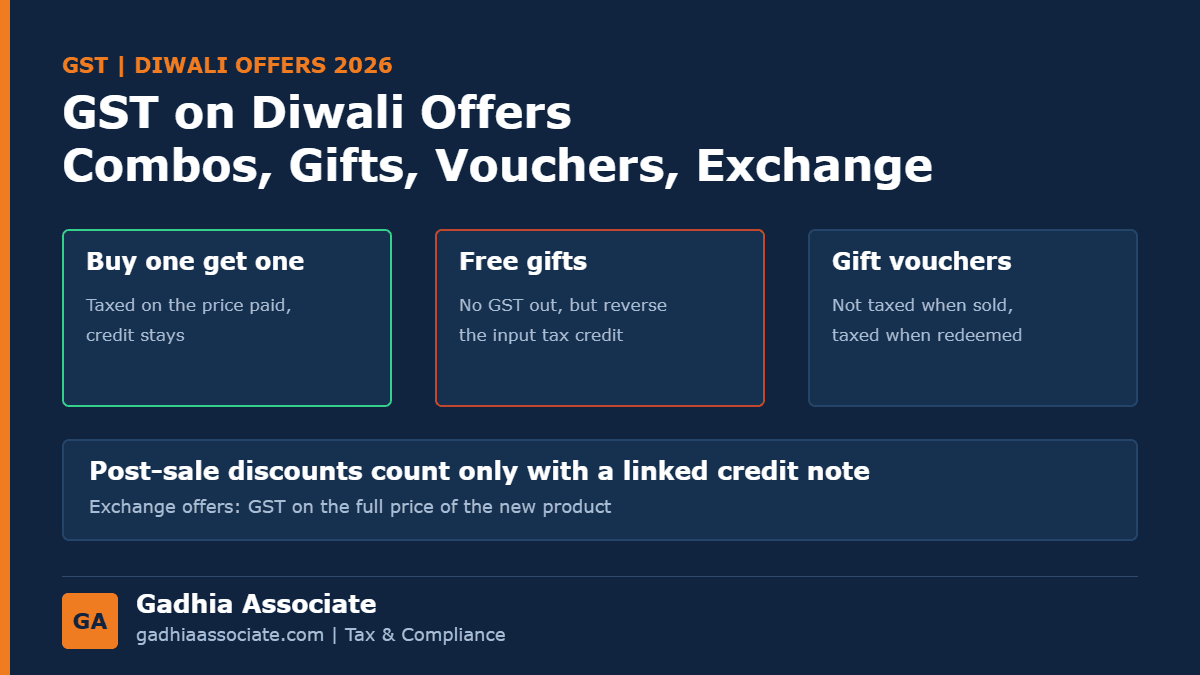
GST on Diwali offers depends on the offer: buy-one-get-one is taxed on the price paid, but truly free gifts force you to reverse input tax credit.
Sanjaybhai runs two electronics showrooms in Junagadh. This Diwali he is offering a free pressure cooker with every refrigerator, 10% cashback after purchase, gift vouchers for big spenders, an exchange scheme for old TVs and a lucky draw for a scooter. His accountant has asked a simple question nobody in the shop can answer: where does the GST go on each of these?
Festive offers are now standard in Gujarat retail, from electronics and mobiles to clothing and jewellery, and each type of offer is treated differently under GST. Here is how they work in 2026.
In short: A combo or buy-one-get-one offer is not a free supply; GST is charged on the price the customer pays, and you keep your input tax credit. Goods given away truly free, such as gifts, free samples or lucky draw prizes, attract no GST on the way out, but you must reverse the input tax credit on them. A discount shown on the invoice reduces the taxable value. A discount given after the sale reduces the value only if it was agreed in advance, linked to the invoices, and given through a GST credit note. Gift vouchers are not taxed when sold; GST applies when they are used. In an exchange offer, GST is charged on the full price of the new product.
Our GST team helps retailers and distributors design offers, bill them correctly and reconcile credit. The details are at the end of this guide.
Combo and buy-one-get-one offers
- Not free: when two items are sold together for one price, the customer pays for both. GST is charged on that price.
- Credit stays: since nothing is given away for free, input tax credit on both items remains available.
- Different rates: if the items carry different GST rates, the bill should show how the price is split, or the higher rate may be applied to the whole.
Truly free gifts, samples and lucky draw prizes
- No GST on the gift: a gift given without any consideration is generally not a supply.
- Reverse the credit: input tax credit on goods given away as gifts or free samples is blocked, so it must be reversed. This is the step most shops miss.
- Gifts with a condition: a gift promised for a minimum purchase is often treated as part of the sale rather than free, but rulings differ, so the offer wording matters.
- Gifts to dealers and staff: gifts to employees above Rs 50,000 a year in value are treated as supplies, and TDS rules apply to gifts to business associates. See TDS on gifts and benefits and Diwali gifts and bonus.
Discounts and cashback
- On the invoice: a discount shown on the bill reduces the taxable value.
- After the sale: reduces the value only if agreed before the sale, linked to specific invoices, and given through a GST credit note against which the buyer reverses the credit.
- Bank and card cashback: cashback paid by a bank or card company does not change your invoice value.
- Distributor schemes: target-based incentives given later are often treated as separate payments rather than discounts. Check the scheme terms before you account for them. Our guide to ITC mismatch notices covers what happens when credit notes do not match.
Gift vouchers and gift cards
- Not taxed when sold: vouchers are neither goods nor services, so no GST is charged at the time of sale.
- Taxed when used: GST applies on the goods or services bought with the voucher, at their rate, when it is redeemed.
- Free vouchers: vouchers given free with a purchase are a discount on the later purchase.
Exchange offers
When a customer hands in an old product and pays the balance, GST is charged on the full price of the new product. The value of the old product only reduces what the customer pays. Buying the old product from an individual customer carries no GST.
Keep the records
- Offer terms and dates, in writing
- A register of free gifts and samples given, with the credit reversed
- Credit notes linked to invoices for every post-sale discount
- Voucher issue and redemption records
Back to Sanjaybhai. The cooker with each refrigerator is billed as a combo at one price, with the split shown, so credit on both stays. The lucky draw scooter is a free gift, so its input tax credit is reversed. Cashback after purchase goes out through credit notes linked to the invoices, as the scheme terms say, and gift vouchers are taxed only when customers redeem them. Exchange bills carry GST on the full price of the new TV.
How we help
- Review festive offers before launch for GST and credit
- Bill formats for combos, exchanges and vouchers
- Credit notes and reconciliation for post-sale discounts
- ITC reversal on gifts and samples
- GST returns and replies to notices on discounts and credit
- Dealer incentive and TDS checks
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. Retailers, distributors and showrooms from Junagadh, Rajkot, Jamnagar, Morbi and Porbandar come to our Junagadh office, where same-day appointments are available. GST work for businesses elsewhere is handled online. See our GST return calendar for the monthly dates.
Running Diwali offers this season? Get them checked for GST before the bills go out. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
Is GST payable on buy-one-get-one free offers?
GST is charged on the price the customer pays for the combination. It is not treated as a free supply, so input tax credit remains available.
Do I have to reverse ITC on free gifts given to customers?
Yes. Input tax credit on goods given away as gifts or free samples is blocked and must be reversed.
Is GST charged on a discount given after the sale?
The discount reduces the taxable value only if it was agreed in advance, linked to the invoices and given through a GST credit note.
Is GST payable when selling gift vouchers?
No. GST is charged when the voucher is used to buy goods or services.
How is GST calculated in an exchange offer?
On the full price of the new product. The old product's value only reduces the amount the customer pays.
Is a lucky draw prize taxable under GST?
The prize given free is not taxed as a supply, but input tax credit on it must be reversed.
Position as of 22 October 2026, including CBIC's clarifications on offers and vouchers. Offer terms decide the treatment, so take advice on your own scheme.