GST Circulars of October 2026: ITC on Demo Vehicles for Agency Dealers, ISD Rules, Vehicle Leasing Charges and NBFC Co-Lending Fees
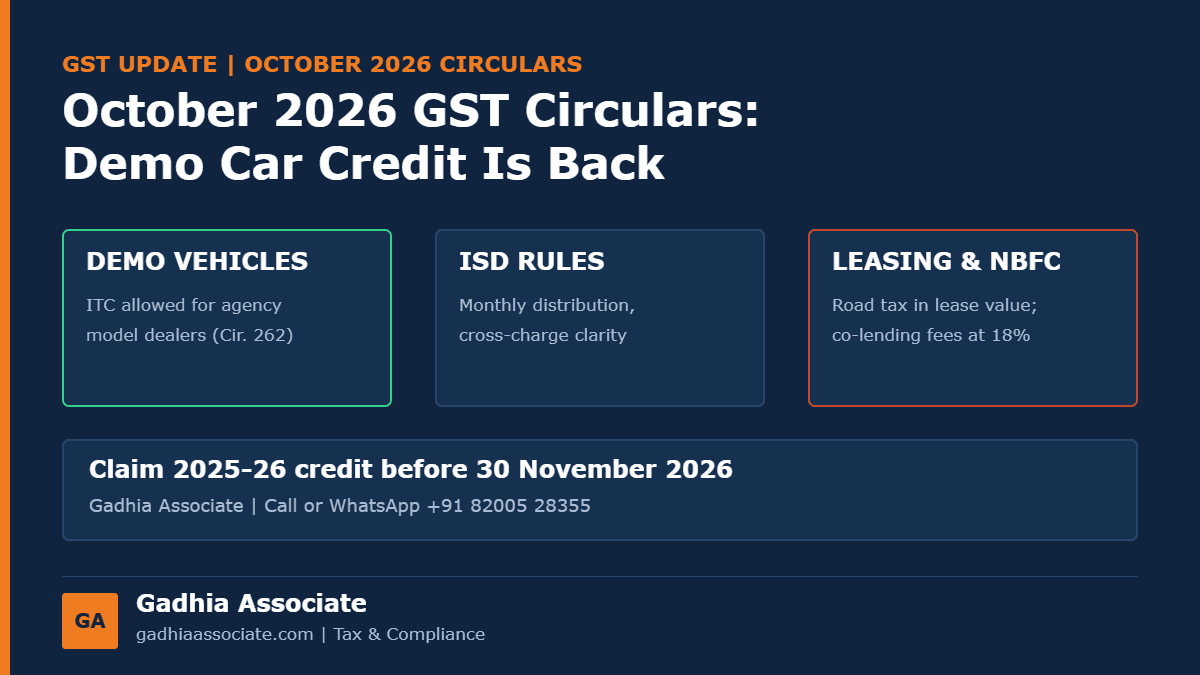
CBIC's October 2026 circulars allow GST credit on demo vehicles for agency dealers, tighten ISD rules and settle GST on leasing and co-lending fees.
Kamleshbhai runs a car dealership in Rajkot. Since the carmaker moved to an agency model, he bills customers on its behalf and earns commission. Because of a 2024 circular, his accountant did not claim GST credit on the demo cars bought in 2025-26, about Rs 28 lakh. His group also has a showroom in Jamnagar under a separate registration, with common advertising and software bills received only in Rajkot.
The GST Council's 57th meeting asked CBIC to clear up several disputed points, and the circulars arrived at the end of October. Some of them put money back in businesses' hands, and some add tax. Here is what they say.
Our team reviews credit claims, ISD set-ups and the effect of these circulars on your business. Call or WhatsApp +91 82005 28355, or see the details at the end of this guide.
Demo vehicles: credit allowed for agency dealers
- The old position: a September 2024 circular allowed credit on demo vehicles for dealers who buy and resell, but one paragraph denied it in the dealer-agency model.
- The change: Circular 262/08/2026-GST withdraws that paragraph. Credit on demo vehicles is not blocked for dealers in the agency model.
- The reason given: demo vehicles serve the same purpose in both models, are bought on tax invoices, are usually capitalised, are held for a set period and are later sold with tax.
- On sale: when a demo vehicle is sold, GST is paid on it as a capital asset, at the higher of the credit taken less 5% for each quarter of use, or tax on the price.
- Cars and credit: for the general rule on cars, see GST and blocked credit on cars.
The time limit matters
- 2025-26 invoices: credit must be claimed by 30 November 2026. See the time limit for claiming ITC.
- Credit claimed and reversed earlier: reversed credit can generally be reclaimed, with records of the reversal.
- Credit never claimed for older years: the time limit for those years may already have passed, so check each year.
Input Service Distributor rules
- Registration: an office that receives bills for input services used by other branches must register as an ISD. See ISD registration.
- Same state: separately registered branches in one state need an ISD if common invoices are issued to different registrations.
- Distribution: credit is distributed in the month it is found eligible, with eligible and ineligible credit shown separately.
- Recipients: each branch must meet the normal conditions for credit on what it receives.
- Excess distribution: can be recovered from the recipients with interest, and the ISD can be penalised.
- Refunds: cross-charge invoices between registrations of the same PAN in the ISD's state are left out of turnover for distribution and refunds.
Leasing, banks and NBFCs
- Vehicle leasing: registration charges, road tax, insurance and FASTag amounts recovered from the lessee are part of the lease value and taxed at the leasing rate.
- Banks: notional interest between a bank's branches under fund transfer pricing is treated as interest, which is exempt.
- NBFC co-lending: sourcing, KYC, underwriting, servicing and collection services an NBFC provides to a partner bank are taxable at 18% on the contract value.
- Other points: a certificate from a specified institution can support the exemption for research grants, and TRAI is not treated as government for exemptions.
- Source: these points are from Circular 266/12/2026-GST as reported, so check the circular text before acting.
What to do now
- Vehicle dealers: list demo vehicles and claim eligible 2025-26 credit before 30 November.
- Multi-branch businesses: check ISD registration and monthly distribution.
- Lessors: bill recoveries such as road tax and insurance as part of the lease value.
- NBFCs: review co-lending agreements and GST on fees.
- Everyone: read these with the 1 November changes. See GST changes from 1 November 2026.
Back to Kamleshbhai. The credit of about Rs 28 lakh on his 2025-26 demo cars is claimed in his October return, well before the 30 November cut-off, and a register tracks each demo car's quarters of use so that the GST on its later sale is worked out correctly. His Rajkot office registers as an ISD and distributes the common advertising and software credit to the Jamnagar showroom every month, with eligible and ineligible credit shown separately.
How we help
- Reviewing blocked and reclaimable credit, including demo vehicles
- ISD registration, monthly distribution and returns
- Cross-charge and refund working for multi-branch businesses
- GST on leasing, NBFC fees and other service contracts
- Replies to notices on credit claims
- Monthly GST compliance and reconciliation
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. Dealers, manufacturers and service businesses from Junagadh, Rajkot, Jamnagar, Morbi and Gondal come to our Junagadh office, where same-day appointments are available. GST work for clients elsewhere is handled online.
Vehicle dealer with unclaimed credit, or running more than one branch? Act before the 30 November cut-off. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
Can a car dealer claim GST credit on demo vehicles?
Yes. Circular 262/08/2026-GST confirms that credit is not blocked, including for dealers working on the agency model.
What is the last date to claim 2025-26 credit?
30 November 2026.
Is GST payable when a demo vehicle is sold?
Yes, at the higher of the credit taken less 5% for each quarter of use, or tax on the sale price.
Who must register as an Input Service Distributor?
An office that receives bills for input services used by other branches with separate registrations.
Is road tax recovered from a lessee part of the lease value?
Yes, as reported from the October circular, it is taxed with the lease at the leasing rate.
Is GST payable on NBFC co-lending fees from banks?
Yes, at 18% on the contract value, as reported from the October circular.
Position as of 9 November 2026, based on Circulars 260/06/2026-GST and 262/08/2026-GST dated 26 October 2026, and Circular 266/12/2026-GST as reported. Read the circular texts and check your own facts before claiming credit.