GST Changes from 1 November 2026: 90% Refund for Inverted Duty, No Rs 1,000 Minimum on Export Refunds, Post-Sale Discounts and Intermediary Exports
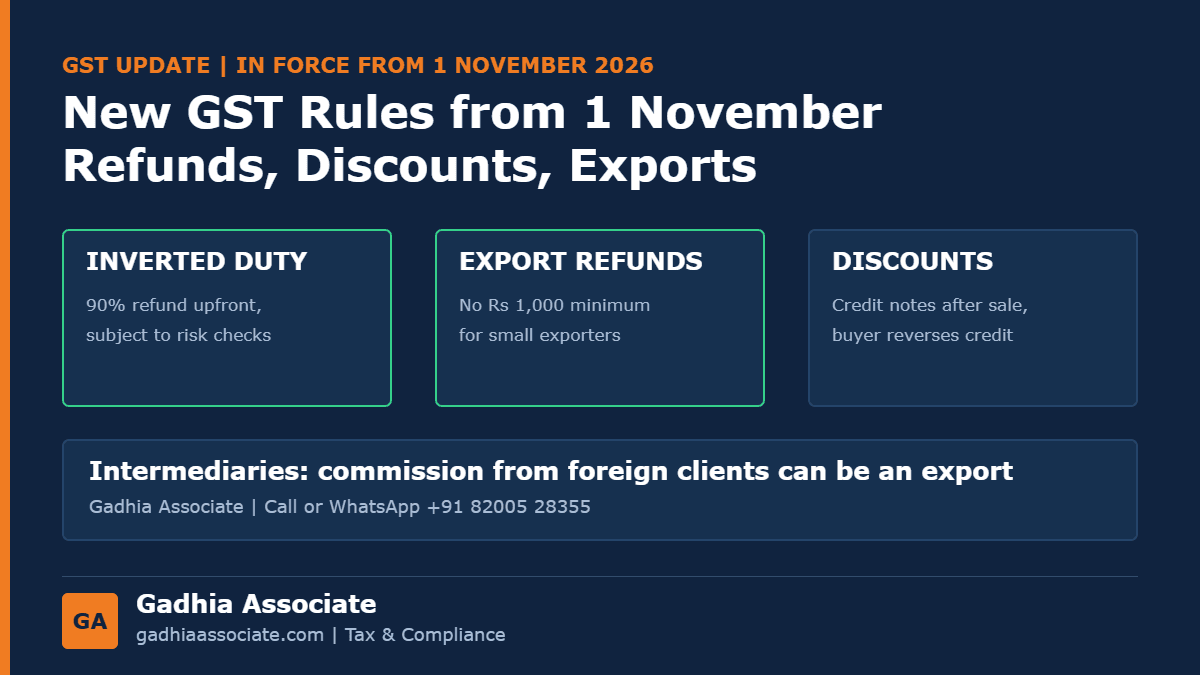
From 1 November 2026, inverted duty refunds get 90% upfront, and post-sale discounts can pass through credit notes without a prior agreement.
Kiritbhai makes rotavators and threshers in Rajkot. Since the GST cut of September 2025, his machines carry 5% while the steel, bearings and gearboxes he buys still carry 18%, so credit piles up and his refund claims take months. He also gives dealers year-end target discounts that were never written into an agreement before the sale. His nephew Ankit, a sourcing agent in Morbi, earns commission in dollars from a buyer in Dubai and has been paying 18% GST on it.
Notifications dated 26 October 2026 bring the first set of GST relief into force from 1 November, while the bigger reforms wait for April 2027. Here is what changes now, who gains, and what to do this week.
Short Answer: GST notifications dated 26 October 2026 bring into force, from 1 November 2026, the refund and discount changes passed in the Finance Act, 2026. Businesses with an inverted duty structure can now get 90% of their refund provisionally, subject to the system's risk checks. The Rs 1,000 minimum no longer applies to refunds of IGST paid on exported goods, which helps small courier and postal exporters. Discounts agreed after a sale can be passed on through credit notes, provided the buyer reverses the matching credit. Intermediaries serving foreign clients now follow the recipient's location, so their commission can be an export. Arrest and notice reforms wait for April 2027.
Our team files refund claims, reviews discount schemes and sets up export billing under the new rules. Call or WhatsApp +91 82005 28355, or see the details at the end of this guide.
What has been notified
- The notifications: dated 26 October 2026, bringing into force from 1 November 2026 the GST amendments made by the Finance Act, 2026.
- Where they come from: GST Council recommendations, with the 57th Council on 8 October 2026 setting the timeline.
- What waits: reforms that need fresh amendments to the GST Acts are aimed at 1 April 2027. See 57th GST Council highlights.
90% provisional refund for inverted duty
- Who gains: businesses whose inputs carry a higher rate than their sales, such as many products moved to 5% in September 2025. See GST 2.0 rates.
- What changes: 90% of the refund claimed can be sanctioned provisionally, as exporters already get, subject to the system's risk checks. The balance follows after verification.
- Which claims: claims filed after 1 November. Pending claims continue under the old process.
- Input services: the formula still works on credit on inputs. Keep credit on input services tracked separately, as the Council has proposed bringing it in later.
- Clean data matters: mismatches between GSTR-2B, GSTR-1 and GSTR-3B are what push a claim out of the fast lane. See why GST refunds get stuck.
Export refunds with no Rs 1,000 minimum
- Before: a refund below Rs 1,000 could not be paid.
- Now: the minimum does not apply to refunds of IGST paid on exports of goods, so small parcels sent by courier or post can be claimed for any amount.
- Who gains: artisans, small online exporters and businesses sending samples abroad. See starting exports from Gujarat.
Post-sale discounts through credit notes
- Before: a discount given after the sale could reduce GST only if it was agreed before or at the time of the sale and linked to specific invoices.
- Now: the prior agreement condition is gone. Year-end, target and scheme discounts can be given through GST credit notes, and the credit note provisions expressly cover them.
- The condition: your tax comes down only if the buyer reverses the matching input tax credit.
- Still separate: payments to dealers for promotion or display work are a service, not a discount. See GST on Diwali offers and discounts.
Intermediaries can now export
- Before: the place of supply for an intermediary was its own location, so commission from foreign principals was taxed in India at 18%.
- Now: the Finance Act, 2026 dropped that special rule, so the place of supply is the recipient's location. Commission from a foreign client can be an export if the other conditions are met, such as payment in foreign exchange.
- Who gains: sourcing and commission agents for foreign buyers, and Indian firms arranging services for overseas principals.
- To bill without GST: file a letter of undertaking and keep the bank's inward remittance records. See billing foreign clients.
- Earlier invoices: reports differ on whether the change applies from the date of the Finance Act in March 2026 or from 1 November. If you paid GST on such commission this year, have it checked for a possible refund.
What to do this week
- Inverted duty units: reconcile credit and file the next claim with matching GSTR-2B data.
- Exporters: list small refunds held back by the old minimum.
- Suppliers: review year-end dealer schemes and ask dealers to reverse credit against your credit notes.
- Intermediaries: file the undertaking and change invoice formats from 1 November.
Back to Kiritbhai. His November claim is filed with GSTR-2B matched to the rupee, so it can qualify for the 90% provisional sanction instead of waiting months. His Diwali target discounts go out as credit notes, and his dealers reverse the matching credit before he reduces his tax. Ankit files his undertaking and bills his Dubai buyer's commission without GST, with the dollars received through his bank, while his invoices from earlier this year are reviewed for a possible refund.
How we help
- Inverted duty and export refund claims, and follow-up
- Reconciliation of GSTR-2B, GSTR-1 and GSTR-3B before a claim
- Credit notes and dealer communication for post-sale discounts
- Export billing, LUT and refunds for intermediaries
- Reviewing past GST paid on commission from foreign clients
- Replies to deficiency memos and refund notices
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. Manufacturers, traders and exporters from Junagadh, Rajkot, Morbi, Jamnagar and Gondal come to our Junagadh office, where same-day appointments are available. GST work for businesses elsewhere is handled online.
Waiting on a GST refund, giving year-end discounts or earning commission from abroad? Get set up for the new rules this week. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
What GST changes apply from 1 November 2026?
90% provisional refunds for inverted duty, no Rs 1,000 minimum on refunds of IGST paid on exported goods, and credit notes for discounts agreed after a sale.
Can inverted duty refunds be sanctioned provisionally now?
Yes. 90% of the claim can be sanctioned provisionally, subject to the system's risk checks.
Is there a minimum amount for GST export refunds now?
No, for refunds of IGST paid on exports of goods. The Rs 1,000 minimum no longer applies to them.
Do post-sale discounts still need an agreement before the sale?
No. A credit note can be issued for a later discount, but the buyer must reverse the matching input tax credit.
Is commission from a foreign client an export under GST?
It can be. The place of supply for intermediaries is now the recipient's location, so commission from a foreign client qualifies if the other export conditions are met.
Are GST arrests removed from 1 November 2026?
No. That needs amendments to the GST Acts, which are aimed at 1 April 2027.
Position as of 28 October 2026, based on the notifications dated 26 October 2026 as reported and the Finance Act, 2026. The notification texts and CBIC circulars decide the conditions in each case, so check before you change your billing.