GST and Income Tax for Coaching Classes and Tuition Centres in 2026: 18% GST, Why Education Exemption Does Not Apply, Cash Fees
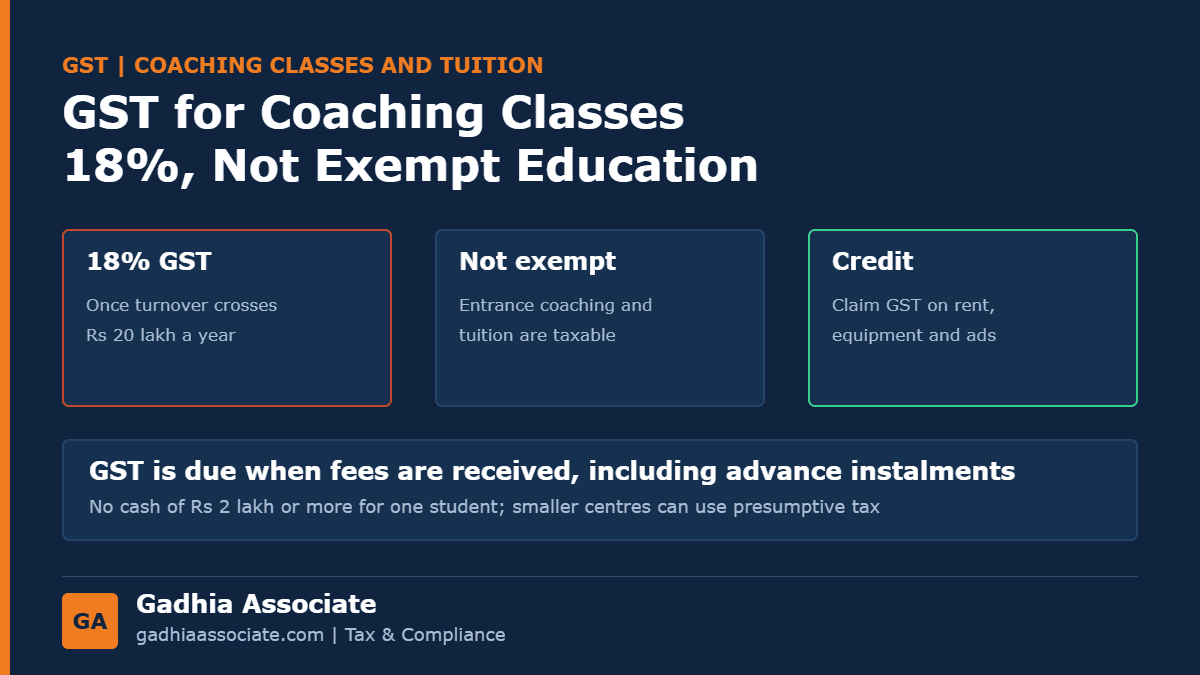
Coaching classes and tuition centres pay 18% GST once turnover crosses Rs 20 lakh, because private coaching does not count as exempt education.
Vipulbhai runs a coaching centre in Rajkot for JEE and NEET aspirants, with 300 students and fees of about Rs 90 lakh a year. He never registered for GST, believing education is exempt. A notice now asks for tax on three years of fees, and his accountant has found that two parents paid the full year's fee of over Rs 2 lakh in cash.
Coaching is one of the fastest-growing businesses in Gujarat, and one of the most misunderstood under GST. Here is how GST and income tax work for coaching classes, tuition centres and training institutes in 2026.
In short: The GST exemption for education covers schools, recognised degrees and approved courses, not private coaching for entrance exams, school tuition, spoken English or computer classes. These are taxed at 18%, with input tax credit, once turnover crosses Rs 20 lakh a year. Study material, test series and online classes supplied with the course are usually taxed as part of the coaching. GST is due when fees are received, including advance and instalment payments. For income tax, coaching is a business: smaller centres can use the presumptive scheme, larger ones keep books and get audited. A coaching centre cannot receive Rs 2 lakh or more in cash for one student's course.
Our team handles GST registration, returns, notices and income tax for coaching classes and training institutes. The details are at the end of this guide.
Why coaching is not exempt
- The exemption: covers services by an educational institution as part of a curriculum for a qualification recognised by law, such as school education, recognised degrees and approved vocational courses.
- Not covered: coaching for JEE, NEET, UPSC, GPSC and other entrance or recruitment exams, school tuition, spoken English, computer and skill classes without a recognised qualification.
- Rate: 18%, with full input tax credit.
Registration, fees and returns
- Registration: needed once turnover crosses Rs 20 lakh a year, counting all branches under the same PAN. See do I need GST registration.
- Advance and instalment fees: GST is due when each payment is received, not when the course ends.
- Refunds: when a student leaves and fees are refunded, the tax is adjusted through a credit note.
- Returns: GSTR-1 and GSTR-3B every month or quarter. See our GST return calendar.
Study material, test series and online classes
- Bundled material: books, notes and test series given as part of the course are usually treated as part of one coaching supply, taxed at 18%.
- Books sold separately: printed books sold on their own are goods with their own GST treatment.
- Online and recorded courses: taxed at 18% like classroom coaching.
Credit you can claim
Because coaching is taxable at 18%, GST paid on classroom rent, furniture, projectors, air-conditioners, software, advertising and professional fees can be set off against the GST you collect. Keep proper tax invoices from suppliers.
Faculty and staff
- Salaried teachers: no GST on salaries, but TDS on salary applies where income crosses the limits.
- Visiting faculty: TDS applies on payments above the limits, and a faculty member with turnover above Rs 20 lakh charges GST. Whether someone is an employee or a consultant changes the rules. See employee or consultant.
Income tax for coaching centres
- Business income: coaching is a business, not a notified profession.
- Presumptive tax: smaller centres can declare 6% of digital and 8% of cash receipts as profit, within the limits. See presumptive taxation.
- Audit: larger centres keep books and get a tax audit once turnover crosses the limit. See tax audit.
- Cash fees: receiving Rs 2 lakh or more in cash for one student's course attracts a penalty equal to the amount. See cash transaction limits.
Back to Vipulbhai. He registers for GST, replies to the notice with a working of the tax on past fees, and claims credit for GST paid on his rent, furniture and advertising for the same period, which reduces what he owes. From this year, fee receipts carry 18% GST, study material is billed as part of the course, and fees of Rs 2 lakh or more come only by bank transfer or UPI. His books are kept for the tax audit his turnover now requires.
How we help
- GST registration and fee receipt formats for coaching centres
- Monthly GST returns and input tax credit on your costs
- Replies to GST notices for past years
- Income tax returns, presumptive or audited
- TDS for salaried and visiting faculty
- Structuring new branches and online courses
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. Coaching classes and training institutes from Junagadh, Rajkot, Jamnagar and Gondal come to our Junagadh office, where same-day appointments are available. Work for institutes elsewhere is handled online.
Running a coaching class without GST registration, or got a notice? Get your position checked this week. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
Is GST applicable on coaching classes?
Yes. Private coaching and tuition are taxed at 18% once turnover crosses Rs 20 lakh a year.
Are coaching classes exempt as education?
No. The exemption covers schools, recognised degrees and approved courses, not coaching for entrance exams or tuition.
Is GST charged on study material given by a coaching class?
Usually yes, as part of the coaching at 18%, when it is supplied with the course.
Can a coaching centre claim input tax credit?
Yes, on rent, furniture, equipment, software, advertising and similar costs used for the coaching.
Can a coaching class accept fees in cash?
Only below Rs 2 lakh for one student's course. Above that, the penalty equals the cash received.
Can a coaching class use presumptive taxation?
Yes, a smaller centre can declare 6% of digital and 8% of cash receipts as profit, within the limits.
Position as of 22 October 2026. GST rates are as notified from 22 September 2025, and the income tax rules described continue under the Income-tax Act, 2025. Exemptions depend on the course and the institution, so take advice on your own facts.