Setting Up a Company in Dubai or Abroad from India in 2026: ODI Rules, 400% Limit, Annual Performance Report by 31 December and Tax
A company in Dubai or abroad can be set up from India under the ODI rules, but it needs bank reporting and a return every 31 December.
Hardikbhai exports groundnuts and sesame from Junagadh. His Gulf buyers want to deal with a Dubai company, so he plans to open one in a free zone, fund it from his savings account and run it from his Junagadh office. His friends say it is simple, and on the Dubai side it is. On the Indian side, the money he sends, the way he holds the shares and where he runs the company from each have rules that can cost him far more than the set-up fee.
Gujarat businesses are opening companies in Dubai, Singapore, the UK and the US in large numbers. Indian law allows it, through the overseas investment rules under FEMA, and it brings yearly reporting and tax questions of its own. Here is how it works in 2026.
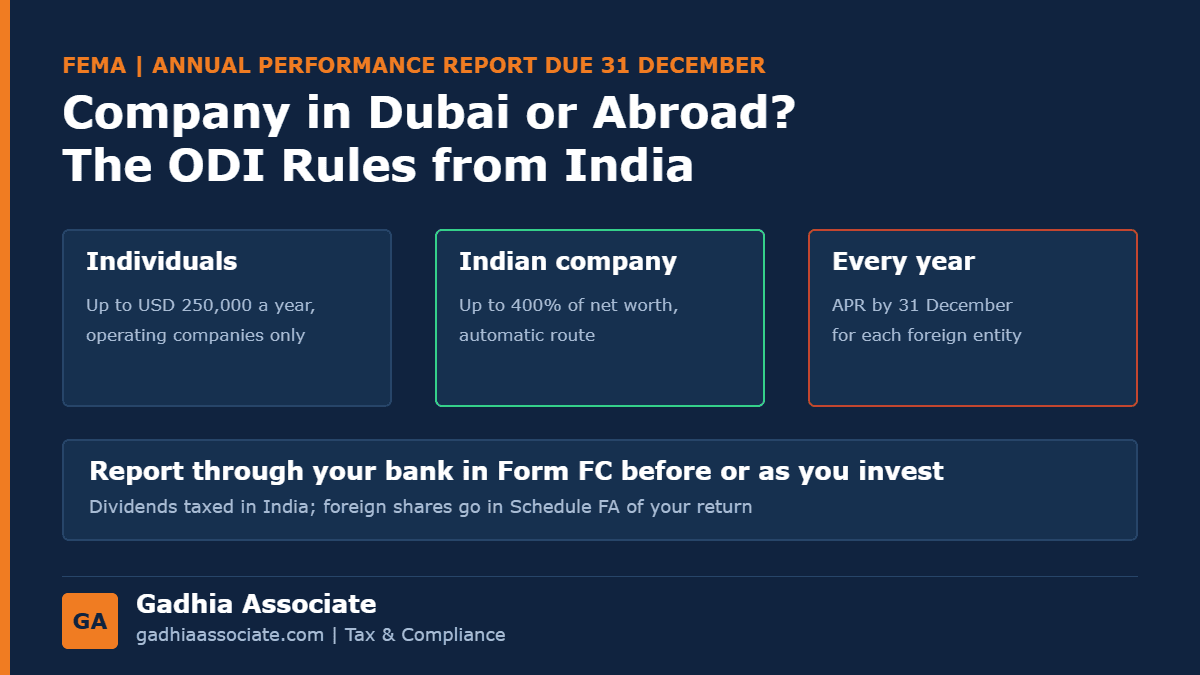
In short: Under the Overseas Investment Rules, 2022, a resident individual can invest abroad within the Liberalised Remittance Scheme limit of USD 250,000 a year, and can hold a controlling or 10%-plus stake (ODI) only in an operating company that is not in financial services. An Indian company or LLP can invest up to 400% of its net worth under the automatic route. Each investment is reported through your bank in Form FC, the RBI allots a unique number to the foreign entity, and an Annual Performance Report is due by 31 December every year for each foreign entity. Late reporting brings late fees and blocks further investment until it is regularised. On tax, dividends from the foreign company are taxed in India, a foreign company that is really run from India can be taxed as an Indian resident, and the shares must be shown in the foreign assets schedule of your return.
Our FEMA and tax team handles ODI structuring, bank reporting, Annual Performance Reports and the Indian tax side. The details are at the end of this guide.
Should you invest personally or through your Indian business?
- Personally: within USD 250,000 a year under LRS. ODI by an individual is allowed only in an operating company, not one in financial services, and an individual cannot use the foreign company to hold further subsidiaries under its control.
- Through an Indian company or LLP: up to 400% of its net worth as per the last audited balance sheet, under the automatic route, with RBI approval needed above USD 1 billion in a year. This suits trading and operating businesses, and keeps the foreign company's income tied to your business accounts.
- Small, passive holdings: less than 10% with no control is portfolio investment (OPI), with lighter rules.
- Round-tripping: a foreign company that invests back into India is allowed only if the structure does not exceed two layers of subsidiaries.
Reporting to the RBI through your bank
- Before sending money: choose your authorised dealer bank and route the investment through it.
- Form FC: report the ODI to the bank, which uploads it to the RBI. The foreign entity gets a unique identification number.
- Later changes: fresh investment, loans to the foreign company, guarantees and sale or closure are reported too.
- Annual Performance Report: due by 31 December every year for each foreign entity, based on its accounts for the year.
- Late reporting: attracts a late submission fee, and until the delay is regularised you cannot make further investment or exit.
The Indian tax side
- Dividends: dividends from the foreign company are taxed in India at normal rates, with credit for tax paid abroad under the tax treaty.
- Run from India: a foreign company whose key management and commercial decisions are in substance made in India can be treated as resident in India and taxed on its global income. The rule applies to companies with turnover above Rs 50 crore. Board meetings, decisions and staff abroad matter.
- Foreign assets schedule: residents must show foreign shares, bank accounts and signing authority in Schedule FA of the income tax return. If past years were missed, the FAST-DS 2026 scheme is open till 31 December 2026; see our guide to FAST-DS 2026.
- Sending the money: remittances under LRS attract TCS above the threshold. See TCS on foreign remittance.
- The UAE side: UAE corporate tax is 9% on taxable income above AED 375,000, and free zone companies can get 0% on qualifying income if they meet the conditions.
Mistakes we see
- Investing personally in a company that is in financial services, or that holds its own subsidiaries
- Paying the set-up costs from India without routing them as investment through the bank
- No Annual Performance Report for years, which blocks the exit when the company is later sold or closed
- Running the foreign company entirely from India, with every decision taken in Junagadh
- Not showing the foreign shares and bank account in Schedule FA
Back to Hardikbhai. Since the Dubai company will trade his own export goods, his Indian private limited company makes the investment, within 400% of its net worth, and reports it in Form FC through its bank. The Dubai company keeps its own accounts and board decisions in Dubai, the first Annual Performance Report is diarised for 31 December, and the shares go into Schedule FA. Dividends, when paid, are taxed in India with credit for any UAE tax.
How we help
- Choose the right route: personal LRS, Indian company or LLP, ODI or OPI
- Form FC and later filings through your bank
- Annual Performance Reports every 31 December, and regularising past delays
- Tax planning for dividends, foreign tax credit and residence of the foreign company
- Schedule FA reporting and FAST-DS disclosures
- Exit, sale or closure of the foreign company
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. Exporters and business families from Junagadh, Rajkot, Jamnagar, Porbandar and Morbi come to our Junagadh office, where same-day appointments are available. FEMA and tax work for clients elsewhere in India is handled online. Our guide on the new FEMA export rules covers the export side.
Planning a company in Dubai or abroad, or already have one without the RBI filings? Get it structured and reported correctly. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
Can an Indian individual open a company in Dubai?
Yes, under LRS within USD 250,000 a year, as long as the company is an operating business not in financial services, and the investment is reported through your bank.
What is the due date of the Annual Performance Report for ODI?
31 December every year, for each foreign entity, based on its accounts for the year.
How much can an Indian company invest abroad?
Up to 400% of its net worth as per the last audited balance sheet, under the automatic route.
Is dividend from a Dubai company taxable in India?
Yes, for a resident of India, at normal rates, with credit for any tax paid abroad under the treaty.
What if I did not file the Annual Performance Report?
File it with the late submission fee. Until the delay is regularised, you cannot make further investment in or exit from that company.
Do I need to show the foreign company in my income tax return?
Yes. Residents must report foreign shares and bank accounts in Schedule FA, even if no income was earned.
Position as of 14 October 2026. FEMA rules are as in the Overseas Investment Rules and Regulations, 2022 and the RBI's directions, and tax rules as carried into the Income-tax Act, 2025. Structures abroad depend on your facts, so take advice before you send money.