Tax Audit Due Date Extended to 21 October 2026 and ITR to 21 November: Who Gets the Extra Time and What Is Still Due
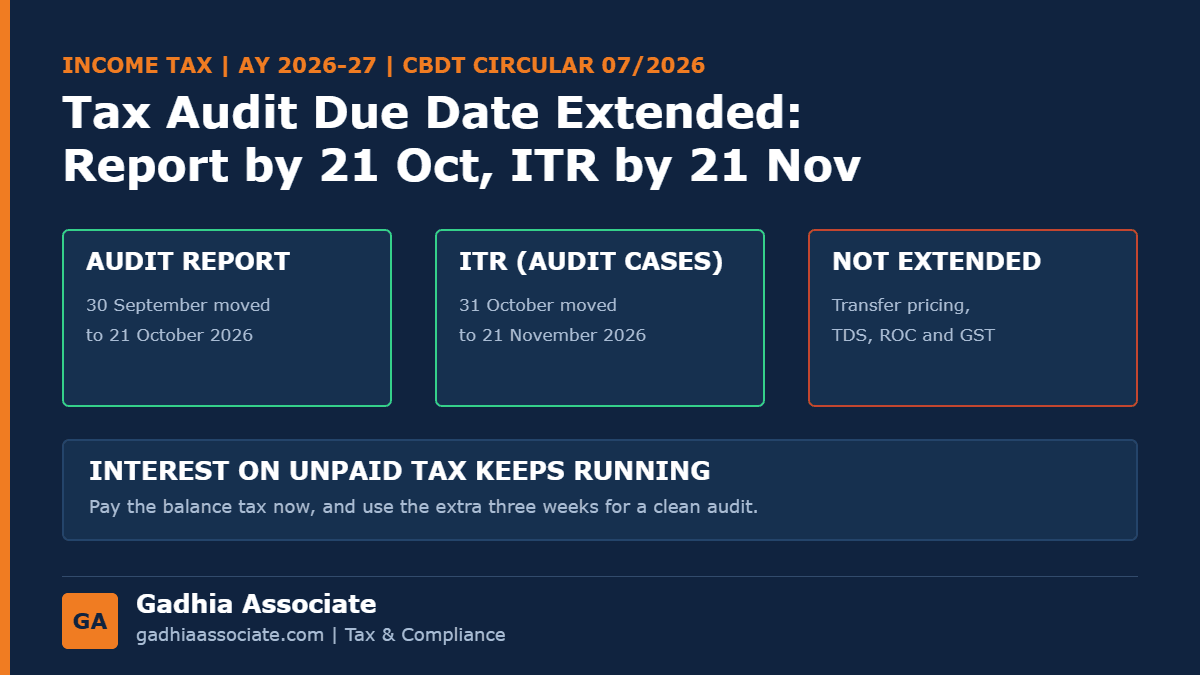
The tax audit due date for AY 2026-27 is now 21 October 2026, and the ITR for audit cases is due by 21 November, under CBDT Circular 07/2026.
The extension came on 28 September, two days before the deadline. For businesses whose books were still being closed, and for auditors juggling GST annual returns, ROC filings and late utilities at the same time, it means three more weeks. It is not a holiday. Here is exactly who gets the extra time, what has not moved, and how to use the weeks well.
In short: By Circular No. 07/2026 dated 28 September 2026, issued under Section 119 of the Income-tax Act, 1961, the date for furnishing audit reports for the previous year 2025-26 (AY 2026-27) moves from 30 September to 21 October 2026. The due date of the return for companies, for businesses and professionals whose accounts must be audited, and for partners of audited firms moves from 31 October to 21 November 2026. Transfer pricing cases are not covered. Interest on unpaid tax keeps running, and other deadlines, such as the TDS return and ROC filings, stay where they were.
What are the new dates?
- Tax audit report in Form 3CA or 3CB with Form 3CD: 21 October 2026, instead of 30 September.
- Income tax return for audit cases: 21 November 2026, instead of 31 October.
- Transfer pricing cases: no change. Form 3CEB is due by 31 October and the return by 30 November, as before.
Who gets the extra time?
The extension applies to the persons in serial number 2 of the due date table under Section 139(1):
- Companies
- Businesses and professionals whose accounts must be audited under the Income-tax Act or any other law, including those who moved out of presumptive tax and now need an audit
- Partners of firms whose accounts must be audited
Trusts and institutions whose accounts must be audited fall in the same group for the return. Since the circular extends the date for audit reports under the Act, a trust's audit report in Form 10B or 10BB should also get the new date, but read the circular against your own case before relying on it. If you are not sure whether an audit applies to you at all, our guide to who needs a tax audit sets out the limits.
What has not been extended?
- Interest: interest for short payment of advance tax keeps running until you pay. Pay the balance tax now, even if the return is filed later.
- TDS return for July to September 2026: still due by 31 October. See our guide to the Q2 TDS return and the new forms.
- Company and LLP filings: AOC-4, MGT-7 and LLP Form 8 follow their own dates under company and LLP law. Our note on LLP annual compliance has the LLP dates.
- GST: monthly and quarterly returns, and the annual return, are not affected.
- Returns without audit: the 31 August date for non-audit business returns has passed. A belated return can still be filed by 31 December 2026, with a late fee.
What if the audit report is still late?
If the report is not furnished by 21 October, a penalty of 0.5% of turnover or gross receipts, up to Rs 1.5 lakh, can be levied under Section 271B, unless there was a reasonable cause. A return filed after 21 November attracts a late fee of up to Rs 5,000 and interest, and a business loss in a late return cannot be carried forward.
How to use the three extra weeks
- Close the books properly: bank reconciliations, stock valuation, and confirmations from debtors and creditors.
- Reconcile turnover with your GST returns and the AIS before the auditor does.
- Check payments to MSME suppliers made after 45 days, which are disallowed under Section 43B(h). Our note on late payments to MSME vendors explains the cost.
- Review TDS on all expenses, since TDS not deducted or not paid leads to disallowance.
- Check cash payments above Rs 10,000 and loans taken or repaid in cash, which the audit report must disclose.
- Pay any balance tax, then finalise the return with the audited figures.
What we do for you
- Complete pending tax audits within the extended date
- Reconcile books with GST returns, the AIS and TDS records before the audit
- Work out the balance tax and interest, and get it paid in time
- File the return for companies, firms, partners and audited individuals by 21 November
- Handle the TDS return, ROC and LLP filings that are not extended
- Reply to penalty notices for late audit reports, with a reasonable cause where it exists
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients across Saurashtra and Gujarat, with a 5.0 Google rating from more than 100 reviews. Traders, manufacturers, professionals, firms and companies from Junagadh, Rajkot, Jamnagar, Veraval, Porbandar and Amreli come to our Junagadh office, where same-day appointments are available. Audit and return work is handled online as well, so we also work with businesses outside Gujarat. Fixed-fee and monthly plans are available.
Audit still pending? Three weeks is enough if you start now. Call or WhatsApp +91 82005 28355. The first consultation is free.
Frequently asked questions
What is the new tax audit due date for AY 2026-27?
21 October 2026, extended from 30 September 2026 by CBDT Circular No. 07/2026.
What is the new ITR due date for audit cases?
21 November 2026, extended from 31 October 2026, for companies, audited businesses and professionals, and partners of audited firms.
Is the due date extended for transfer pricing cases?
No. Cases covered by Section 92E keep the original dates.
Is the ITR due date extended for non-audit cases?
No. The 31 August date has passed. A belated return can be filed by 31 December 2026 with a late fee.
Will interest be charged if I file by 21 November?
Interest for short payment of advance tax continues until the tax is paid, so pay any balance tax as early as possible.
What is the penalty for not getting a tax audit done?
0.5% of turnover or gross receipts, up to Rs 1.5 lakh, under Section 271B, unless there is a reasonable cause.
Position as of 30 September 2026, based on CBDT Circular No. 07/2026 dated 28 September 2026. Read the circular for its exact scope before relying on it for your case.