GST and Income Tax for Contractors in 2026: 2% GST TDS on Government Contracts, TDS on Bills, Mobilisation Advances, Retention Money and Cement at 18%
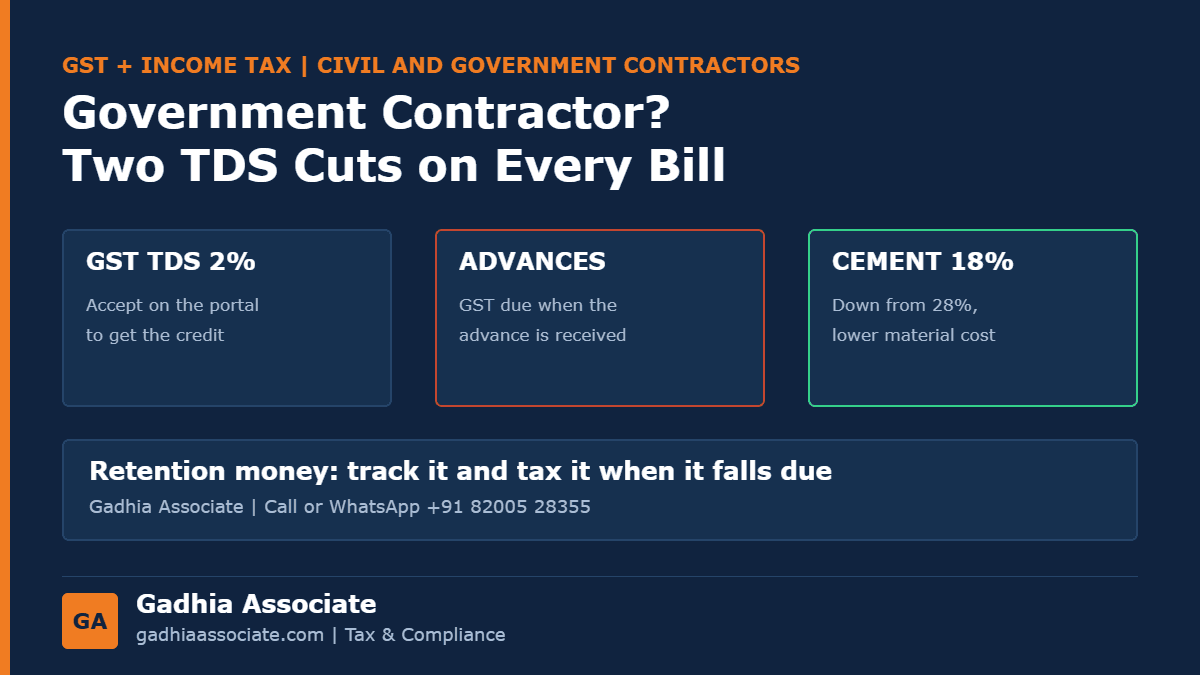
Government contractors face TDS twice, under GST and income tax, and mobilisation advances and retention money have their own tax timing rules.
Bhupatbhai is a civil contractor in Junagadh who builds roads and school buildings for the district panchayat and the state roads department, with a turnover of about Rs 6 crore. Every running bill comes with 2% GST TDS and 1% income tax TDS deducted, 5% retention money is held back for the defect period, and a new contract has just paid him a mobilisation advance. His accountant has not charged GST on the advance, and the GST TDS credit has been sitting unclaimed on the portal for months.
Contracting is one of the largest businesses in Saurashtra, and also one where tax is lost in small gaps between the bill, the deductions and the returns. Here is how GST and income tax work for contractors in 2026.
Our team handles GST, TDS credits, books and audits for contractors and sub-contractors. Call or WhatsApp +91 82005 28355, or see the details at the end of this guide.
GST on works contracts
- The rate: most works contracts carry 18%. Concessional rates for some government and housing works were revised from 22 September 2025, so confirm the rate for each contract.
- Credit: GST on cement, steel, machinery hire and sub-contractors is claimed as input tax credit.
- Cement: down from 28% to 18%, so contracts priced before the cut now cost less to execute.
- Rate changes mid-contract: bills raised after a rate change carry the new rate; check the GST clause in your contract.
GST TDS on government contracts
- Who deducts: government departments, local authorities, government agencies and notified public sector bodies.
- How much: 2% of the taxable value, where the contract value exceeds Rs 2.5 lakh.
- Getting the credit: the deductor files its TDS return, and you accept the entry on the GST portal, after which it reaches your cash ledger.
- Use it: the credit pays your GST, and any surplus can be claimed as a refund. See why GST refunds get stuck.
Advances, running bills and retention
- Mobilisation advance: GST is due when an advance for a works contract is received, not later when the work is billed.
- Running bills: GST is due on each bill raised, including the part held back as retention.
- Retention for income tax: retention money is usually taxed when it becomes payable under the contract, after the defect period, so track it separately in the books.
- Deposits: earnest money and security deposits are not income; they are your money held by the department.
Income tax for contractors
- TDS on your bills: 1% for individual and HUF contractors, 2% for firms and companies, credited against your tax.
- Match the credit: check every deduction in your annual tax statement against your bills. See AIS and Form 26AS.
- Your own TDS: deduct TDS when you pay sub-contractors and machinery hire, or 30% of those payments can be disallowed.
- Presumptive scheme: small contractors can declare 6% of digital receipts as profit, within the turnover limits; larger ones keep books and get a tax audit. See tax audit.
- Paying suppliers: dues to micro and small suppliers not paid within 45 days can be disallowed. See the 45-day payment rule.
Labour and site compliance
- PF and ESIC: for workers on your rolls, once the thresholds are crossed. See PF and ESIC registration.
- Labour cess: construction welfare cess, usually 1% of the cost, is often deducted from bills.
- E-way bills: needed when you move taxable material above Rs 50,000 to site.
Back to Bhupatbhai. GST is paid on the mobilisation advance for the month it was received, with interest for the delay, and every running bill now shows GST on its full value, retention included. The GST TDS entries are accepted on the portal, and the credit pays his monthly GST. His income tax TDS is matched bill by bill with his annual tax statement, retention money is tracked in a separate account and offered to tax as each release falls due, and TDS is deducted on payments to his two sub-contractors. With turnover above the presumptive limit, his books are audited and his return filed by the audit due date.
How we help
- GST registration, returns and rate checks for each contract
- GST TDS acceptance, credit and refunds
- Income tax TDS matching and returns for contractors
- Books, retention and advance tracking, and tax audit
- TDS on sub-contractors and machinery hire
- PF, ESIC and labour compliance support
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. Contractors from Junagadh, Rajkot, Porbandar, Amreli and Veraval come to our Junagadh office, where same-day appointments are available. Work for contractors elsewhere is handled online.
Government contractor with TDS credits piling up or GST gaps? Get your bills, credits and books aligned. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
What is GST TDS on government contracts?
Government bodies deduct 2% of the taxable value on contracts above Rs 2.5 lakh, which the contractor claims as credit after accepting it on the GST portal.
What is the TDS rate on payments to contractors?
1% for individual and HUF contractors, and 2% for others.
Is GST payable on a mobilisation advance?
Yes. For a works contract, GST is due when the advance is received.
When is retention money taxed for income tax?
Usually when it becomes payable under the contract, after the defect period.
What is the GST rate on works contracts?
Most carry 18%. Concessional rates for some government and housing works changed from 22 September 2025, so check each contract.
Can a contractor use presumptive taxation?
Yes, within the turnover limits, declaring 6% of digital receipts as profit.
Position as of 3 November 2026, under the GST law as amended from 22 September 2025 and the Income-tax Act, 2025. Rates depend on the exact contract and recipient, so check before you bill.