Returning to India After Years Abroad? RNOR Status, NRE and FCNR Accounts, Foreign Income and What to Disclose in 2026
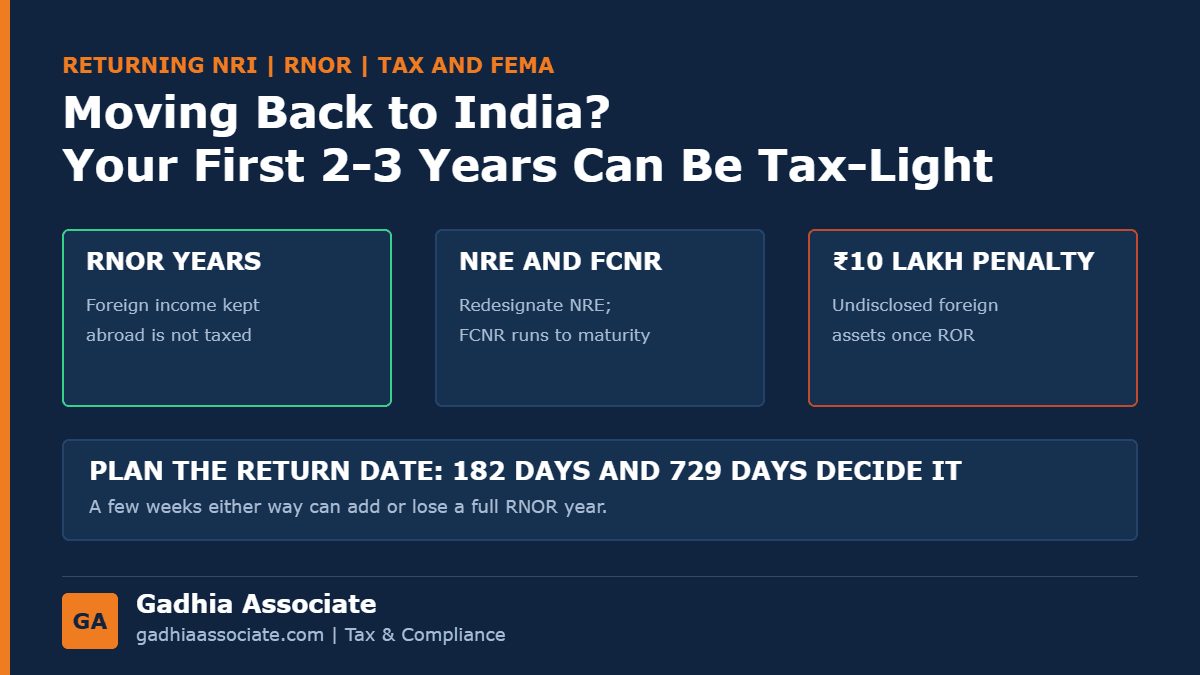
A returning NRI usually gets two or three years as RNOR, when income earned abroad stays out of Indian tax, if the move is planned well.
After 18 years in Leicester, a Porbandar couple decided to come home. They had a UK pension, savings and shares in UK accounts, a rented flat there, and NRE fixed deposits in India. They landed in June, told nobody at the bank, kept the NRE deposits running as before, and asked the UK pension provider to pay into their Indian account because it was easier. Three years later, the question from the tax department was simple: why were none of the UK assets in the return?
None of this was dishonest. It was just unplanned. The first years after coming back are the ones where planning saves the most tax, and where mistakes are easiest to make. This article explains how residential status works when you return, what RNOR status gives you, what to do with your NRE, NRO and FCNR accounts, and what you must start disclosing, and when.
Short answer: Your tax residence is decided each tax year by the days you spend in India, under Section 6 of the Income-tax Act, 2025, which keeps the old tests unchanged. Most people returning after ten years or more are first "resident but not ordinarily resident" (RNOR). While you are RNOR, Indian tax applies to income earned or received in India, but not to foreign income earned and received abroad. NRE accounts must be converted to resident accounts when you return, while FCNR deposits can run until maturity and their interest stays tax-free while you are RNOR. Once you become "resident and ordinarily resident", you must report all foreign assets and income in your return, and non-disclosure can attract a penalty of Rs 10 lakh a year under the Black Money Act.
How is your residential status decided in the year you return?
Residence is tested separately for each tax year, April to March. You are resident in India for a tax year if either of these applies:
- You are in India for 182 days or more in that year, or
- You are in India for 60 days or more in that year and 365 days or more in the four years before it.
For an Indian citizen or person of Indian origin who is only visiting India, the 60 days become 182 days, or 120 days if Indian income exceeds Rs 15 lakh. Someone who has come back for good is generally not treated as visiting, so if you spent 365 days or more in India in the previous four years, 60 days in the year of return can be enough to make you resident.
What is RNOR, and how long does it last?
A resident is "not ordinarily resident" for a tax year if either of these is true:
- You were a non-resident in nine out of the ten tax years before that year, or
- You were in India for 729 days or less in total in the seven tax years before that year.
Someone returning after ten or more years abroad usually gets two RNOR years, and a third if the day count allows it. The date you land can decide which.
An example: two people have lived abroad for 15 years, visiting India for about three weeks every year. After returning, both stay in India right through the next year.
- Returns on 1 August 2026: RNOR for 2026-27 and 2027-28 under the nine-out-of-ten test. For 2028-29, the days in India in the previous seven years come to about 714, within 729, so a third RNOR year follows.
- Returns on 1 June 2026: the same first two RNOR years, but the count for 2028-29 rises to about 775 days, so the third year is lost.
Plan the date with the day count in front of you. A few weeks either way can add or lose a full RNOR year.
What is taxed in India while you are RNOR?
- Taxed: all income earned or received in India, such as Indian salary, rent, interest on NRO and resident deposits, and gains on Indian shares, funds and property.
- Taxed: foreign income from a business controlled in India or a profession set up in India.
- Not taxed: other foreign income earned and received abroad, such as salary for work done abroad, rent from a flat abroad, foreign interest and dividends, and gains on selling foreign shares or property.
Two points matter in practice. First, where income is first received counts. A foreign pension or rent paid straight into an Indian account is received in India and becomes taxable. Keep it paid into your foreign account, and bring money across later as savings. Second, the RNOR years are the natural window to sell foreign assets you plan to exit, because the gain is outside Indian tax, though the other country may still tax it.
What happens to your NRE, NRO and FCNR accounts?
- NRE and NRO accounts: under RBI rules, these must be redesignated as resident accounts once you return to live in India. Tell your bank in writing soon after you land. NRE interest is tax-free only while you are a non-resident under FEMA, so interest after your return date is taxable even if the bank has not yet changed the account.
- FCNR deposits: these can run until maturity at the agreed rate, and their interest stays tax-free while you are RNOR.
- RFC account: a Resident Foreign Currency account lets you keep foreign currency you bring back, or your NRE and FCNR balances, in foreign currency. Its interest is also generally tax-free while you are RNOR.
- Foreign accounts and assets: FEMA lets you keep the bank accounts, property, shares and pension you built up while living abroad, and the income from them. You do not have to sell them or bring the money back.
- Demat and mutual funds: NRI demat and portfolio investment accounts must be converted, and your KYC with the depository, fund houses and insurers updated to resident status.
What must you disclose, and from when?
- While RNOR: file your Indian return as RNOR. Schedule FA, the foreign assets schedule, applies only to residents who are ordinarily resident.
- From the first year you are ordinarily resident: your worldwide income is taxable, and every foreign bank account, share, pension, insurance policy and property must be reported in Schedule FA, even if it earns nothing.
- Penalty: not reporting foreign assets can attract a penalty of Rs 10 lakh for each year under the Black Money Act. Since October 2024, the penalty does not apply where the total value of foreign assets other than immovable property is within Rs 20 lakh, but foreign property must always be reported.
- Foreign tax credit: where the other country also taxes your income, such as UK tax on rent, claim credit in India through Form 67, which becomes Form 44 under the new rules. File it on time, or the credit can be denied.
Before you start filing as a resident, make sure your NRI years are clean. If you missed Indian returns while abroad, our guide to NRI returns that were never filed explains how to fix them. Once you are resident, money you send abroad falls under the Liberalised Remittance Scheme, with TCS on larger amounts, as explained in TCS on foreign remittance.
A checklist for your first year back
- Before booking the ticket, count your days in India for the last seven years and pick the return date.
- File a final tax return in the country you are leaving, and get a tax residence certificate if you need one.
- Within a few weeks of landing, ask the bank to redesignate NRE and NRO accounts, open an RFC account if useful, and let FCNR deposits run to maturity.
- Keep foreign pension, rent and interest paid into foreign accounts during the RNOR years.
- Update KYC for demat, mutual funds and insurance, and your address and status with every bank.
- Decide which foreign assets to keep and which to sell while you are RNOR.
- From the first ordinarily resident year, report everything in Schedule FA and claim foreign tax credit.
What we do for you
- Work out your residential status year by year, and the best return date
- Plan the RNOR years: which income to keep abroad and which assets to sell
- Guide the conversion of NRE, NRO, FCNR and demat accounts under FEMA
- File your Indian returns with the right status, Schedule FA and foreign tax credit
- Apply the tax treaty with the country you left, including in the year you move
- Handle notices about foreign income, foreign assets or high-value transactions
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients across Saurashtra and Gujarat, with a 5.0 Google rating from more than 100 reviews. Families moving back from the UK, the US, Canada, Africa and the Gulf to Junagadh, Rajkot, Porbandar, Jamnagar, Veraval and Amreli come to our Junagadh office, where same-day appointments are available. We also work online with NRIs while they are still abroad, so planning can start before the move. Fixed-fee and monthly plans are available.
Planning to move back to India in the next year? Talk to us before you book the ticket. Call or WhatsApp +91 82005 28355. The first consultation is free.
Frequently asked questions
What is RNOR status for a returning NRI?
RNOR means resident but not ordinarily resident. You are resident for the year, but foreign income earned and received abroad is not taxed in India. It applies if you were a non-resident in nine of the previous ten years, or in India for 729 days or less in the previous seven years.
How many years can I stay RNOR after returning to India?
Usually two years after a long stay abroad, and sometimes three, depending on your days in India in the previous seven years.
Is my foreign pension taxable in India after I return?
Not while you are RNOR, if it is paid into a foreign account. Once you are ordinarily resident, it is taxable in India, subject to the tax treaty and credit for tax paid abroad.
What should I do with my NRE account after returning to India?
Ask the bank to redesignate it as a resident account, or move the balance to an RFC account. Interest after your return date is taxable.
Is FCNR interest taxable after I return?
FCNR deposits can continue until maturity, and their interest remains tax-free while you are RNOR.
Do I have to show my foreign bank accounts in my Indian tax return?
Yes, from the first year you are resident and ordinarily resident, in Schedule FA. Missing it can attract a Rs 10 lakh penalty under the Black Money Act.
Position as of 28 September 2026. The residence tests are in Section 6 of the Income-tax Act, 2025, which applies from 1 April 2026. Bank practice under FEMA varies, and tax treaties differ by country. Take advice on your own dates, accounts and assets before you move.