Land Acquisition Compensation and Income Tax in 2026: When Highway and Railway Compensation Is Tax-Free, TDS Refunds and Interest on Enhanced Compensation
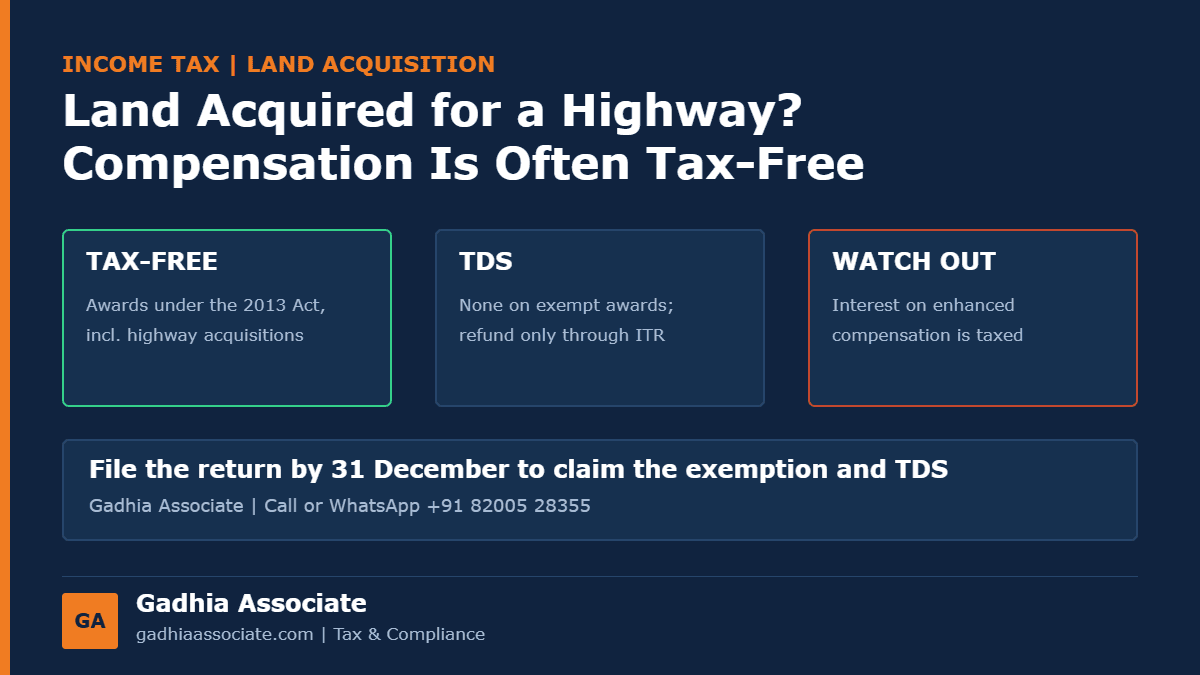
Land acquisition compensation for highways, railways and other projects is often tax-free, but only if your income tax return claims it correctly.
Jayantibhai and his two brothers own 14 bigha of farmland on the edge of Gondal. Part of it was acquired for a national highway bypass, and in January 2026 the land acquisition office paid an award of Rs 2.4 crore, including Rs 18 lakh for a well, a pump room and mango trees. It deducted Rs 1.8 lakh of TDS on the structures, treating them as non-agricultural. None of the brothers files income tax returns, and the department has now sent them a message about a high-value receipt in their annual statements.
Highways, railway lines, canals and industrial corridors are taking land across Saurashtra, and families receiving compensation are often unsure whether it is income, what the TDS means and whether they need to file a return. Here is how the tax works in 2026.
Short Answer: Compensation under an award or agreement made under the 2013 land acquisition law is not taxed, whether the land is agricultural or not, because section 96 of that Act bars income tax on it, and CBDT has confirmed this; only private purchase agreements under section 46 are left out. Courts have applied the exemption to land taken for national highways and other central projects, though the department sometimes disputes it. Urban farmland used for agriculture for two years is also exempt under the income tax law. No TDS should be deducted on exempt compensation; if it was, file a return to get it back. Interest on delayed or enhanced compensation is usually taxed, with a 50% deduction.
Our team checks land acquisition awards, files the returns that claim the exemption and recovers TDS deducted on compensation. Call or WhatsApp +91 82005 28355, or see the details at the end of this guide.
When compensation is tax-free
- Awards under the 2013 Act: section 96 of the Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013 says no income tax is levied on an award or agreement made under it.
- CBDT confirmation: Circular 36/2016 clarified that such compensation is not taxable even though the Income-tax Act has no matching exemption of its own.
- Whole award: it covers agricultural and non-agricultural land, and the amounts in the award for structures, wells and trees.
- The exception: an agreement under section 46 of that Act, where a private buyer purchases land and rehabilitation applies, is not covered.
- Urban farmland: the income tax law separately exempts compulsory acquisition of agricultural land in urban areas, if it was used for farming by you, a parent or your HUF for two years before the transfer.
- Rural farmland: agricultural land outside the specified urban limits is not a capital asset at all. See selling agricultural land in Gujarat.
Highways, railways and other central projects
- Their own Acts: land for national highways, railways and similar projects is acquired under separate central laws listed in the 2013 Act.
- Same compensation rules: since 1 January 2015, the 2013 Act's compensation provisions apply to those acquisitions too.
- Court view: the Chhattisgarh High Court held in September 2025 that the tax exemption applies to land acquired for a national highway, and several tribunals have taken the same view.
- The department's view: some officers still treat highway compensation as taxable, so claim the exemption openly and keep the papers ready.
- Older awards: for acquisitions under the old 1894 law, check the dates carefully, because the 2013 Act exemption may not apply.
TDS on compensation
- Rate: 10% on compensation for non-agricultural property, once payments in a year cross Rs 5 lakh (Rs 2.5 lakh before April 2025).
- Agricultural land: no TDS at all.
- Exempt awards: the TDS provision itself says no deduction is made on compensation exempt under the 2013 Act, and the Andhra Pradesh High Court confirmed this in August 2026.
- If TDS was deducted anyway: it shows in your annual tax statement and can be recovered only through a return. See AIS and Form 26AS.
- Older years: an updated return cannot be used to claim a refund, so a late claim may need a condonation request to the tax department.
Interest on delayed and enhanced compensation
- The general rule: interest received on compensation or enhanced compensation is taxed as income in the year it is received, with a deduction of 50%.
- The dispute: the Delhi High Court held in 2024 that such interest is taxable, while some tribunals have treated interest forming part of an exempt award as exempt too.
- Enhanced compensation: the extra amount granted by a reference court or High Court follows the original award: exempt where the award is exempt, and taxed in the year of receipt where it is not.
- Plan the year: a large interest receipt can push up the tax for that year, so time other income and investments with care.
When compensation is taxable
- Negotiated sales: land sold by negotiation outside the 2013 Act, to a company or a public body, is a normal sale for capital gains.
- Non-exempt acquisitions: capital gains are taxed in the year the compensation is first received, at 12.5% on long-term gains, with an option of 20% with indexation for land held since before 23 July 2024.
- Saving the tax: reinvestment in a house or in specified bonds can reduce it. See saving capital gains tax on property.
- Joint owners: each co-owner reports his or her own share.
Filing the return
- Report it as exempt: show the compensation as exempt income, naming the law it is exempt under, not as capital gains.
- Keep the papers: the acquisition notification, the award, the break-up of compensation, the 7/12 extract and the bank credit.
- Answer the annual statement: a return that reports the receipt settles the high-value transaction query before it becomes a notice.
- Deadline: the return for 2025-26 can still be filed until 31 December 2026. See belated and updated returns.
- Farm income: agricultural income goes in the same return. See agricultural income.
Back to Jayantibhai. The land was taken under the National Highways Act after 1 January 2015, so the award falls under the 2013 Act's compensation rules. Each brother files his return for 2025-26 before 31 December 2026, showing his one-third share of Rs 2.4 crore as exempt compensation, with the award, the notification and the 7/12 extract on file. The Rs 1.8 lakh of TDS is claimed back in the returns of the brothers in whose PANs it was deducted, and the returns settle the high-value receipt query. Their appeal for higher compensation is pending, and any interest they receive later will be planned for in that year's return.
How we help
- Checking whether your compensation is exempt
- Income tax returns that report exempt compensation correctly
- TDS refund claims, including condonation for older years
- Interest on enhanced compensation and tax planning for that year
- Capital gains and reinvestment where compensation is taxable
- Replies to income tax messages and notices on high-value receipts
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. Farmers and landowners from Junagadh, Gondal, Jetpur, Keshod and Rajkot come to our Junagadh office, where same-day appointments are available. Families elsewhere in Gujarat are handled online.
Received compensation for land taken for a highway, railway or other project? Get the return and the TDS refund right before 31 December. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
Is land acquisition compensation taxable in India?
Not when it is paid under an award or agreement under the 2013 land acquisition law, other than a section 46 agreement. Urban farmland compulsorily acquired is also exempt under the income tax law.
Is compensation for national highway land taxable?
Courts have held it exempt, because the 2013 Act's compensation rules apply to highway acquisitions since 1 January 2015, though the department sometimes disputes it.
Is TDS deducted on land acquisition compensation?
Not on agricultural land, and not on compensation exempt under the 2013 Act. Otherwise, 10% once payments in a year cross Rs 5 lakh.
How do I get back TDS deducted on compensation?
File an income tax return claiming the exemption and the TDS credit. For older years, a condonation request may be needed.
Is interest on enhanced compensation taxable?
Generally yes, in the year it is received, with a 50% deduction, though some tribunals have treated it as exempt.
Do I need to file a return if my compensation is exempt?
It is strongly advisable, to report the receipt, claim any TDS and avoid a notice on a high-value transaction.
Position as of 17 November 2026, under the land acquisition law of 2013, CBDT Circular 36/2016, the Income-tax Act, 2025 and court rulings to date. Every award is different, so get your own documents checked.