GST Demand Orders for 2022-23 Due by 31 December 2026: Replying to the Show Cause Notice, Personal Hearing, Time-Barred Orders and Appeal
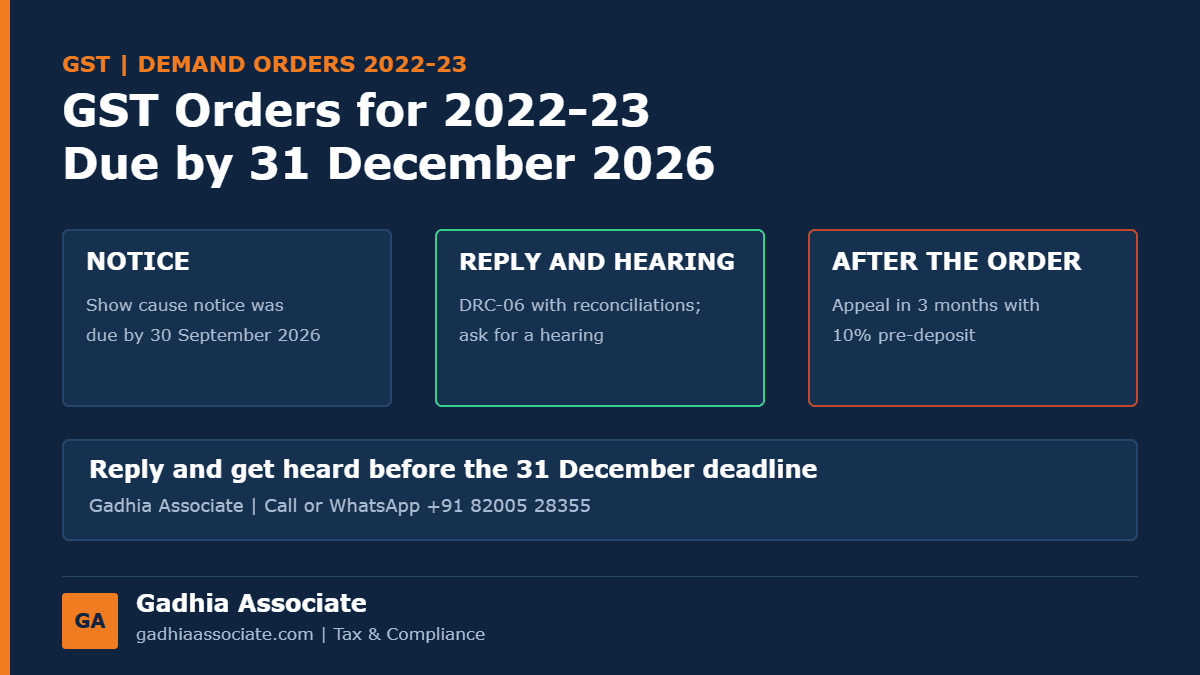
GST officers must pass demand orders for 2022-23 by 31 December 2026, so a reply and hearing in the next few weeks can decide what you pay.
Dineshbhai runs an electrical goods trading firm in Rajkot. In September 2026 he received a show cause notice for 2022-23 demanding Rs 8.6 lakh: Rs 5.2 lakh of credit not seen in GSTR-2B when he claimed it, Rs 1.9 lakh of credit from a supplier whose registration was later cancelled, and Rs 1.5 lakh of difference between GSTR-1 and GSTR-3B. His accountant did not reply. Last week the portal showed a personal hearing in early December.
December is the busiest month of the year for GST orders, because every open notice for 2022-23 has to be decided before the time limit runs out. Here is what the deadline means and what to do before it.
Our team replies to GST notices, attends personal hearings and files appeals against demand orders. Call or WhatsApp +91 82005 28355, or see the details at the end of this guide.
Why 31 December 2026 matters
- Normal cases: an order under section 73 must be issued within three years of the due date of the annual return. For 2022-23 that date was 31 December 2023, so the order deadline is 31 December 2026.
- Notice deadline: the show cause notice must come at least three months earlier, that is by 30 September 2026.
- Fraud cases: where fraud, suppression or wilful misstatement is alleged under section 74, the limit is five years, to 31 December 2028.
- Later years: 2023-24 runs to 31 December 2027, and from 2024-25 a new combined provision with its own time limits applies.
- Missed deadline: if the order is not issued in time, the proceedings are treated as concluded.
If you have a show cause notice
- Read it closely: note each ground, period and amount, and whether it is under section 73 or 74. See how to read a GST notice.
- Reply in DRC-06: with month-wise reconciliations, supplier details, invoices, e-way bills and payment proof.
- Credit mismatches: show where the invoices appeared in later GSTR-2B statements within the time limit. See ITC mismatch notices.
- Cancelled suppliers: prove the purchase was genuine with bills, transport papers and bank payments; courts have protected buyers who can do this.
- Genuine shortfall: pay it with interest in DRC-03 and mention it in the reply. Payment within 30 days of the notice avoids penalty; after that, the penalty is 10% of the tax or Rs 10,000, whichever is higher.
Personal hearing and the order
- Right to be heard: an officer must give a hearing before passing an adverse order, and you can ask for one in writing.
- Adjournments: a hearing can be adjourned up to three times, but not past the deadline.
- Limits on the order: it cannot demand more than the notice, or go beyond the grounds in it.
- Reasons: the order must deal with your reply, and its summary comes in Form DRC-07.
- Watch the portal: orders are often uploaded under additional notices and orders in the last days of December, so check it and your email daily.
After the order
- Appeal: file APL-01 within three months, with one more month for sufficient cause, and pay 10% of the disputed tax; recovery of the rest is stayed. See GST appeals.
- Rectification: errors apparent on the record can be corrected by the officer on an application made within three months.
- Recovery: if the demand is neither paid nor appealed within three months, the department can attach bank accounts. See bank account frozen.
- Lower penalties: the 57th GST Council has recommended lighter penalties in non-fraud cases, which apply only once the law is changed. See 57th GST Council.
Common grounds in 2022-23 notices
- Credit claimed in GSTR-3B above GSTR-2B
- Credit from suppliers whose registration was cancelled from an earlier date
- Differences between GSTR-1 and GSTR-3B
- Credit claimed after the time limit of 30 November 2023. See the time limit for claiming ITC.
- Reverse charge not paid on transport, legal services or rent
- Blocked credit on cars, food or gifts
- Interest on tax paid late
Back to Dineshbhai. His reply, filed before the hearing, shows that the Rs 5.2 lakh of credit relates to invoices his two suppliers reported late, which appeared in his GSTR-2B for later months of 2022-23, well within the time limit. For the Rs 1.9 lakh, he files the supplier's bills, e-way bills and bank payments, and shows that the supplier's registration was active on the invoice dates. The Rs 1.5 lakh difference is reconciled month by month to amendments in later returns. He attends the hearing with the papers, and whatever the order says, he is ready to appeal within three months.
How we help
- Checking notices for time limits and grounds
- Reconciliations and replies in DRC-06
- Representation at personal hearings
- Appeals in APL-01 and stay of recovery
- Rectification and release of attached bank accounts
- Review of 2023-24 returns before the next round of notices
Gadhia Associate has been in practice since 2007 and has handled work for over 7,000 clients, with a 5.0 Google rating from more than 100 reviews. Traders and manufacturers from Junagadh, Rajkot, Jamnagar, Morbi and Gondal come to our Junagadh office, where same-day appointments are available. GST notices for clients elsewhere are handled online.
Got a GST notice or order for 2022-23? Reply and get heard before the 31 December deadline. Call or WhatsApp +91 82005 28355, or message us on WhatsApp. The first consultation is free.
Frequently asked questions
What is the last date for GST demand orders for 2022-23?
31 December 2026 in normal cases, and 31 December 2028 where fraud or suppression is alleged.
Is a GST order for 2022-23 valid if passed after 31 December 2026?
Not in a normal case under section 73. The proceedings are treated as concluded.
How do I reply to a GST show cause notice?
In Form DRC-06, with reconciliations and documents, and ask for a personal hearing.
Can I avoid penalty on a GST notice?
Yes, in a non-fraud case, by paying the tax with interest within 30 days of the notice.
What is the time limit to appeal against a GST order?
Three months from the order, plus one more month for sufficient cause, with a 10% pre-deposit.
Can a GST order demand more than the show cause notice?
No. The order cannot exceed the amount or go beyond the grounds in the notice.
Position as of 17 November 2026, under sections 73, 74, 75, 107 and 161 of the CGST Act. Recommendations of the GST Council apply only once notified, so check the law in force on the date of your order.